2.5%
General inflation
How fast everyday prices rise each year: the central bank’s published target.
FIRE Planner · FIRE calculator for Hong Kong
See when your household could stop working, in Hong Kong dollars, with Hong Kong inflation, a fast-rising medical cost rate and your MPF pre-filled. Free: eight answers after sign-up, about two minutes.
Your Location
| Country | Currency | Inflation | Medical |
|---|---|---|---|
| Hong Kong | HKD | 2.5% | 9.9% |
| India | INR | 4.0% | 12.9% |
| United Kingdom | GBP | 2.0% | 10.0% |
| Singapore | SGD | 2.0% | 16.9% |
Fourteen countries. Every rate shown, every rate yours to change.
FIRE Planner · your FI number in HKD
Your FI number is a year of life after work, divided by the 4% withdrawal rate for Hong Kong, with withdrawal tax allowed for. It is projected in HKD (HK$).
Hong Kong publishes household income rather than wealth, so your peer percentile compares income against the Census and Statistics Department household income statistics.
How the FIRE Planner works →Financial freedom index
An illustrative household. Your own score is computed from your plan and stored, not estimated.
Hong Kong · the rates your plan starts from
A Hong Kong plan starts from these, in HKD. Each is yours to change, and changing yours changes nobody else’s.
2.5%
How fast everyday prices rise each year: the central bank’s published target.
2.07%
School fees, which usually rise faster than everyday prices.
9.9%
Healthcare costs, which rise faster than everyday prices in almost every market.
6.7%
An assumption about the future, shown so you can change it.
4.4%
Lower, because money being drawn on is usually held more cautiously.
4%
What your FI number assumes you draw from your savings in a year.
Portfolio Tracker · Hong Kong schemes in one plan
Each is a row under its own name, beside your stocks, funds and deposits anywhere, in one currency in the Portfolio Tracker.
How the Portfolio Tracker works →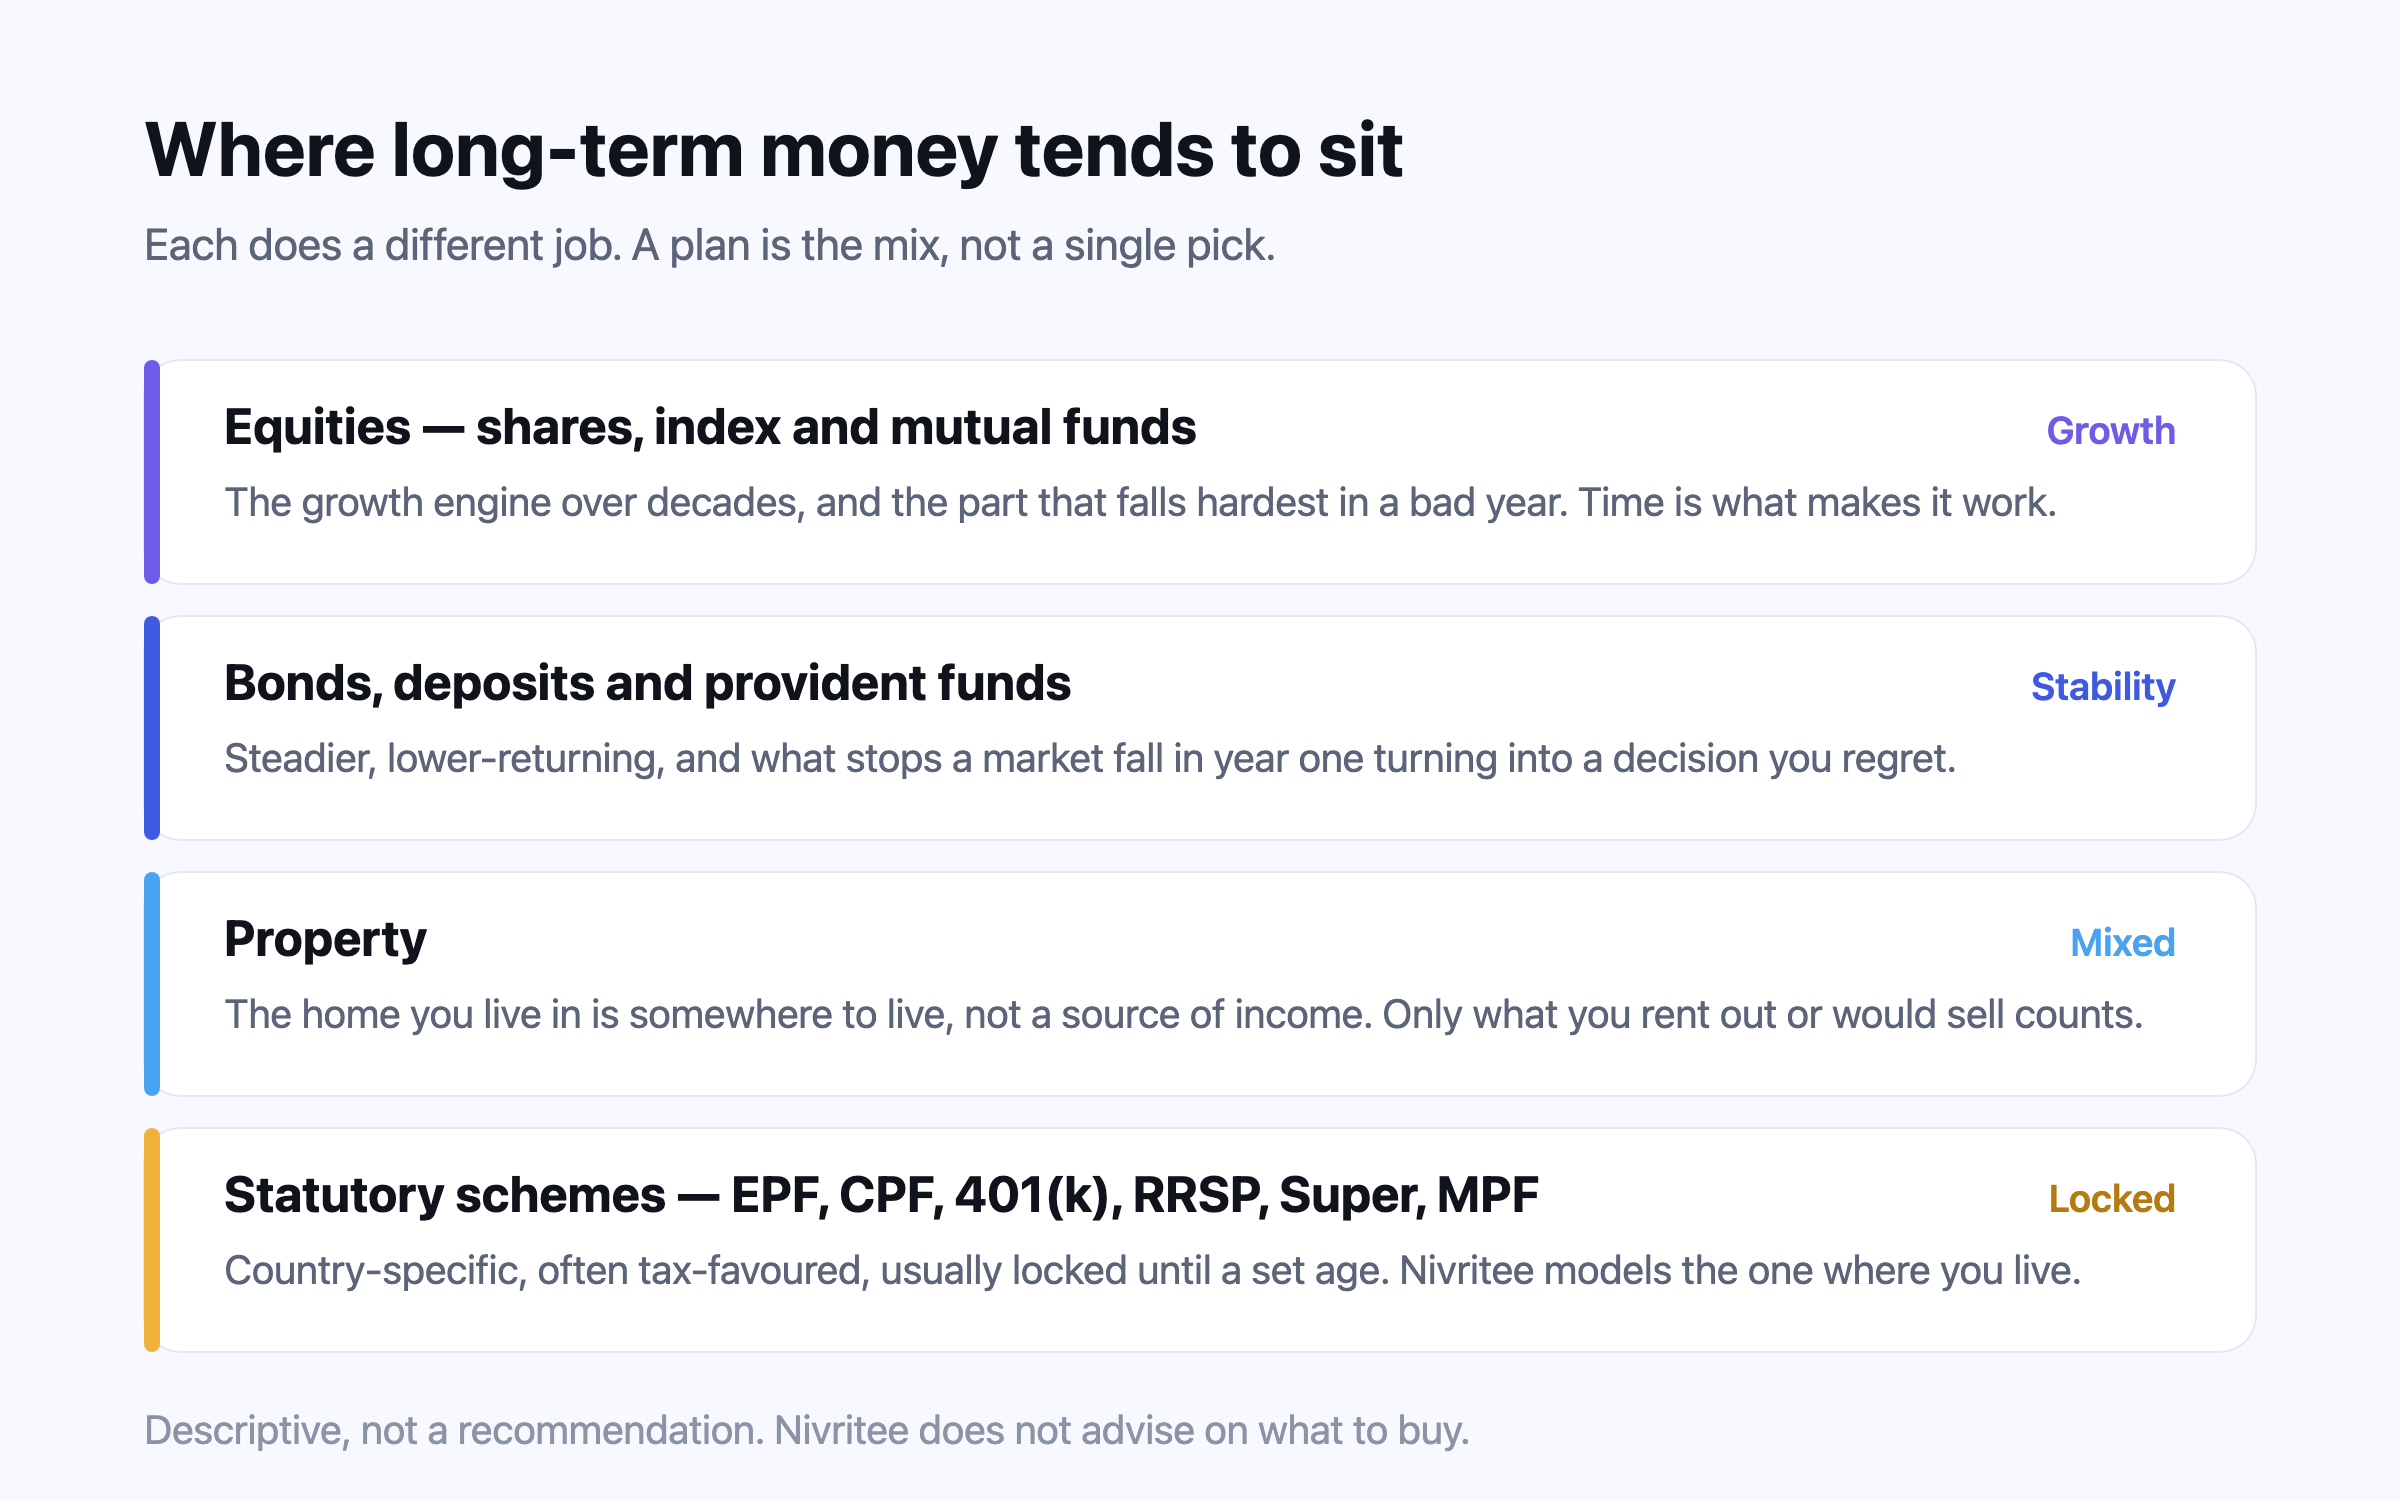
Hong Kong · when the money can be reached
The ages that decide how a FIRE plan bridges the years after the salary stops.
MPF from mandatory contributions can be withdrawn at 65, by lump sum or instalments.
Early retirement from 60 also releases it, once you have stopped all work and declare you will not return to it.
FIRE Planner · Hong Kong
MPF mandatory contributions are 5% each from you and your employer, capped at HK$1,500 a month each on HK$30,000 of income. Above that, a FIRE plan rests on what you save yourself.
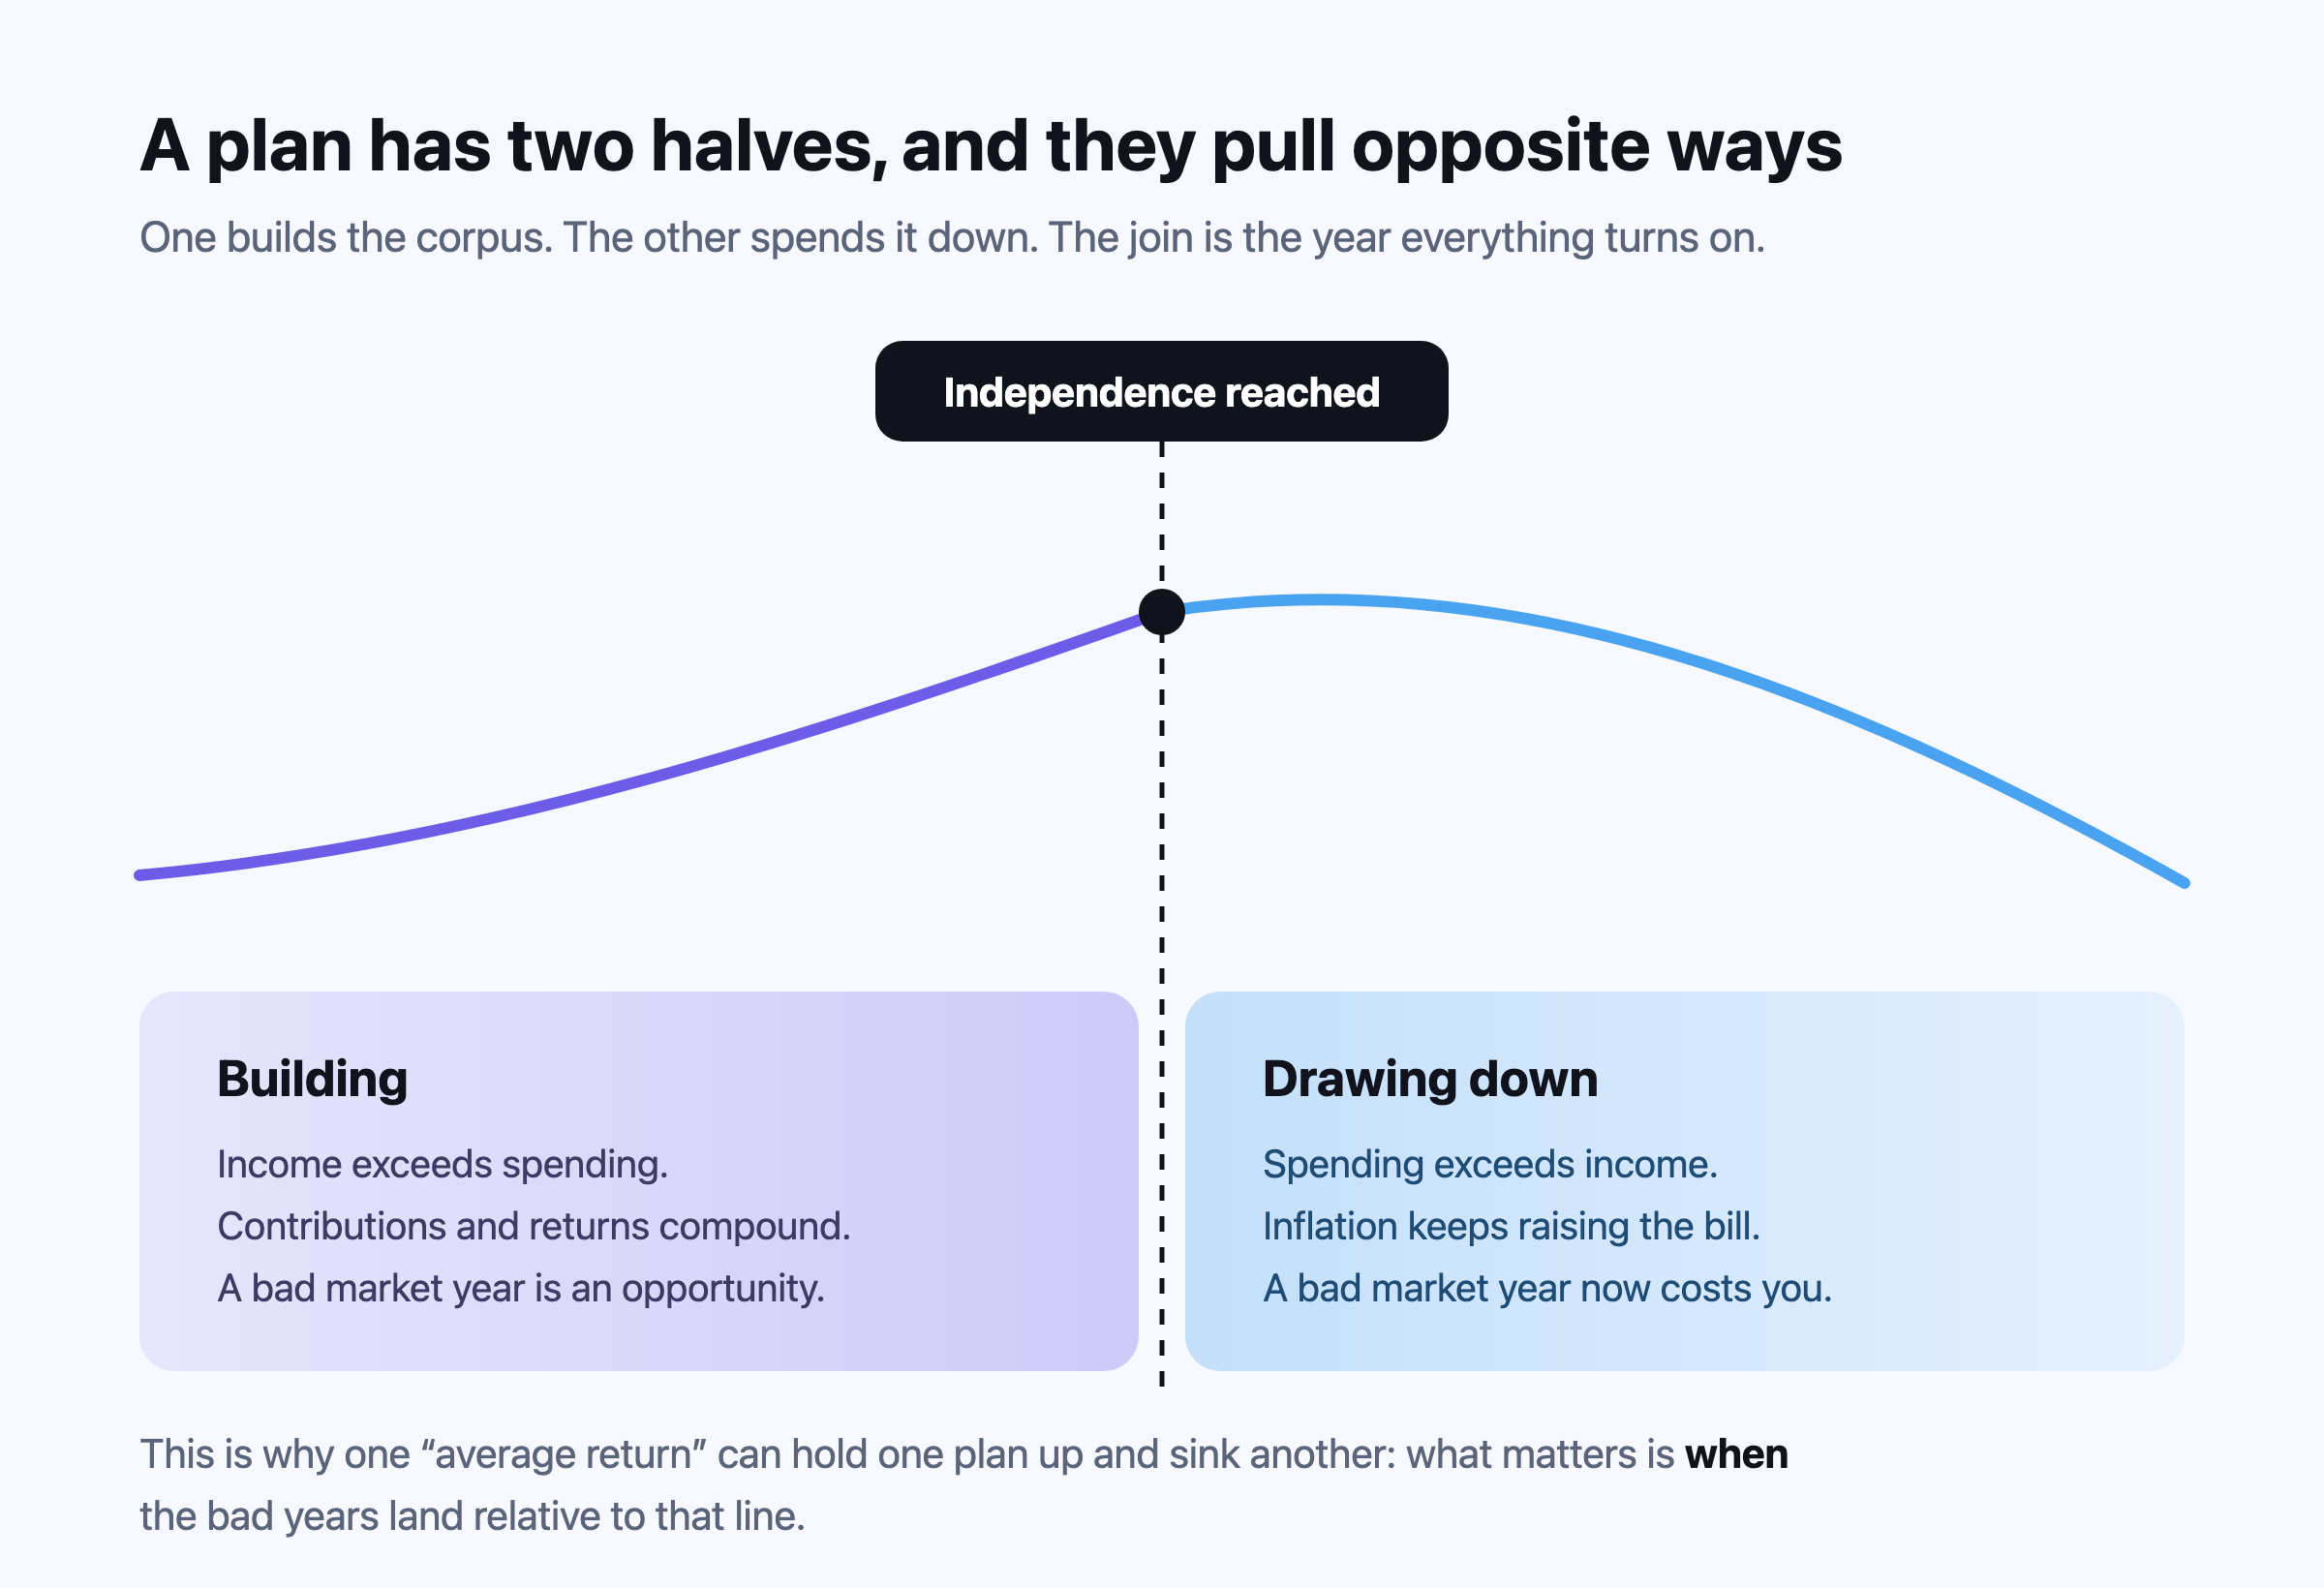
MPF opens at 65, or at 60 if you have stopped working for good. The ledger shows every year your other savings carry before then.
Hong Kong has no capital gains tax, and the Hong Kong dollar is held between HK$7.75 and HK$7.85 to the US dollar, which matters if you hold US investments.
Medical costs rise at their own rate; insurers in WTW’s survey project a 9.9% medical cost trend for Hong Kong in 2026. Hong Kong publishes household income rather than wealth, so your peer percentile compares income with Hong Kong households.
Why Nivritee for Hong Kong
Your Hong Kong plan reads the same figures as every other pillar: what you hold, earn, spend and owe, in every country.
Portfolio Tracker
Stocks, funds and deposits from every country you invest in, valued daily in one home currency, with your actual return (XIRR).
Portfolio Tracker →Cash Flow Tracker
Each month starts from your plan: close it in a minute, see where the money went, and follow your savings rate, ratios and loans month by month. Nothing linked.
Cash Flow Tracker →Money Manager
What you earn, spend and owe, benchmarked against your country, your city and each kind of inflation.
Money Manager →Family Finance
Plan as a couple with your own logins, choose what each of you sees, and give your CA or lawyer read-only access.
Family Finance →Niv
Analyses your portfolio, spending, buckets and plan, runs what-ifs on the real projection, and explains. You decide.
Niv →Freedom Ladder
Survival, Sustenance, Sufficiency, Surplus: how much belongs in each bucket, and whether it is in something that bucket can use.
Freedom Ladder →What only Nivritee does
Most FIRE calculators start from a figure you type. Ours starts from everything your household holds, in every country, in one currency, for both of you.
Indian mutual funds, US stocks, a UK fund and a Gulf deposit in one household figure, converted daily into your home currency.
What you hold today feeds the projection of when you could stop. Portfolio trackers do not plan; FIRE calculators do not track.
Two people, one plan, each choosing what the other sees — and your CA or lawyer sees exactly what you share, read-only.
Fourteen markets’ inflation, schemes and household surveys, so your spending and your percentile are measured where you live.
Ask Niv a what-if and she runs it on your own projection and reports both figures — she never guesses at arithmetic.
No fee, no commissions, no products. Nobody at Nivritee can open your plan.
FIRE calculator Hong Kong · questions
The common rule of thumb is 25 times a year’s spending: a 4% first-year withdrawal, raised with inflation, lasted at least 30 years through US market history in William Bengen’s 1994 study. Nivritee’s FI number uses a 4% withdrawal rate on your own spending, adds your goals and nets off income that keeps paying.
At 65, or from 60 if you have stopped all work and declare you will not return to it, as a lump sum or in instalments.
For most households it is one part. Mandatory contributions stop rising above HK$30,000 a month of income, at HK$1,500 each from you and your employer. Nivritee projects the MPF row beside your other savings and shows whether the whole reaches your FI number.
Yes. Nivritee’s FIRE Planner is free, with no paid tier. Once you have an account it asks eight questions, about two minutes, and projects your plan year by year in Hong Kong dollars with Hong Kong inflation and your MPF. You get your FI number, a 0–100 Financial Freedom Index, eight stress tests and how your household income compares with Hong Kong households.
Free, neutral and private
Nothing here is for sale, so nothing here pushes you anywhere. You read the figures, and you decide.
Find your FI number for Hong Kong.
Eight figures and about two minutes to a first answer. Add the rest when you are ready. Free, no bank login, and nobody at Nivritee can open your plan.