Every country, one currency
Indian mutual funds, US stocks, a UK fund and a Gulf deposit in one household figure, converted daily into your home currency.
NRI portfolio tracker · for Indians who earn abroad
Indian mutual funds, NSE shares, US stocks, a Dubai savings account, EPF and a flat in Pune, in one currency, priced every weekday. Then a FIRE plan for where you will live. No broker login.
Portfolio Tracker
Converted once into INR, before anything is computed.
Portfolio Tracker · NRI investment tracker
Indian mutual funds, NSE and BSE shares, and holdings on NASDAQ, NYSE, London, six European exchanges and the Stock Exchange of Thailand. Each is priced at its daily close and converted once, at a checked rate.
NRE, NRO and foreign accounts go in as deposits.
Every market the Portfolio Tracker covers →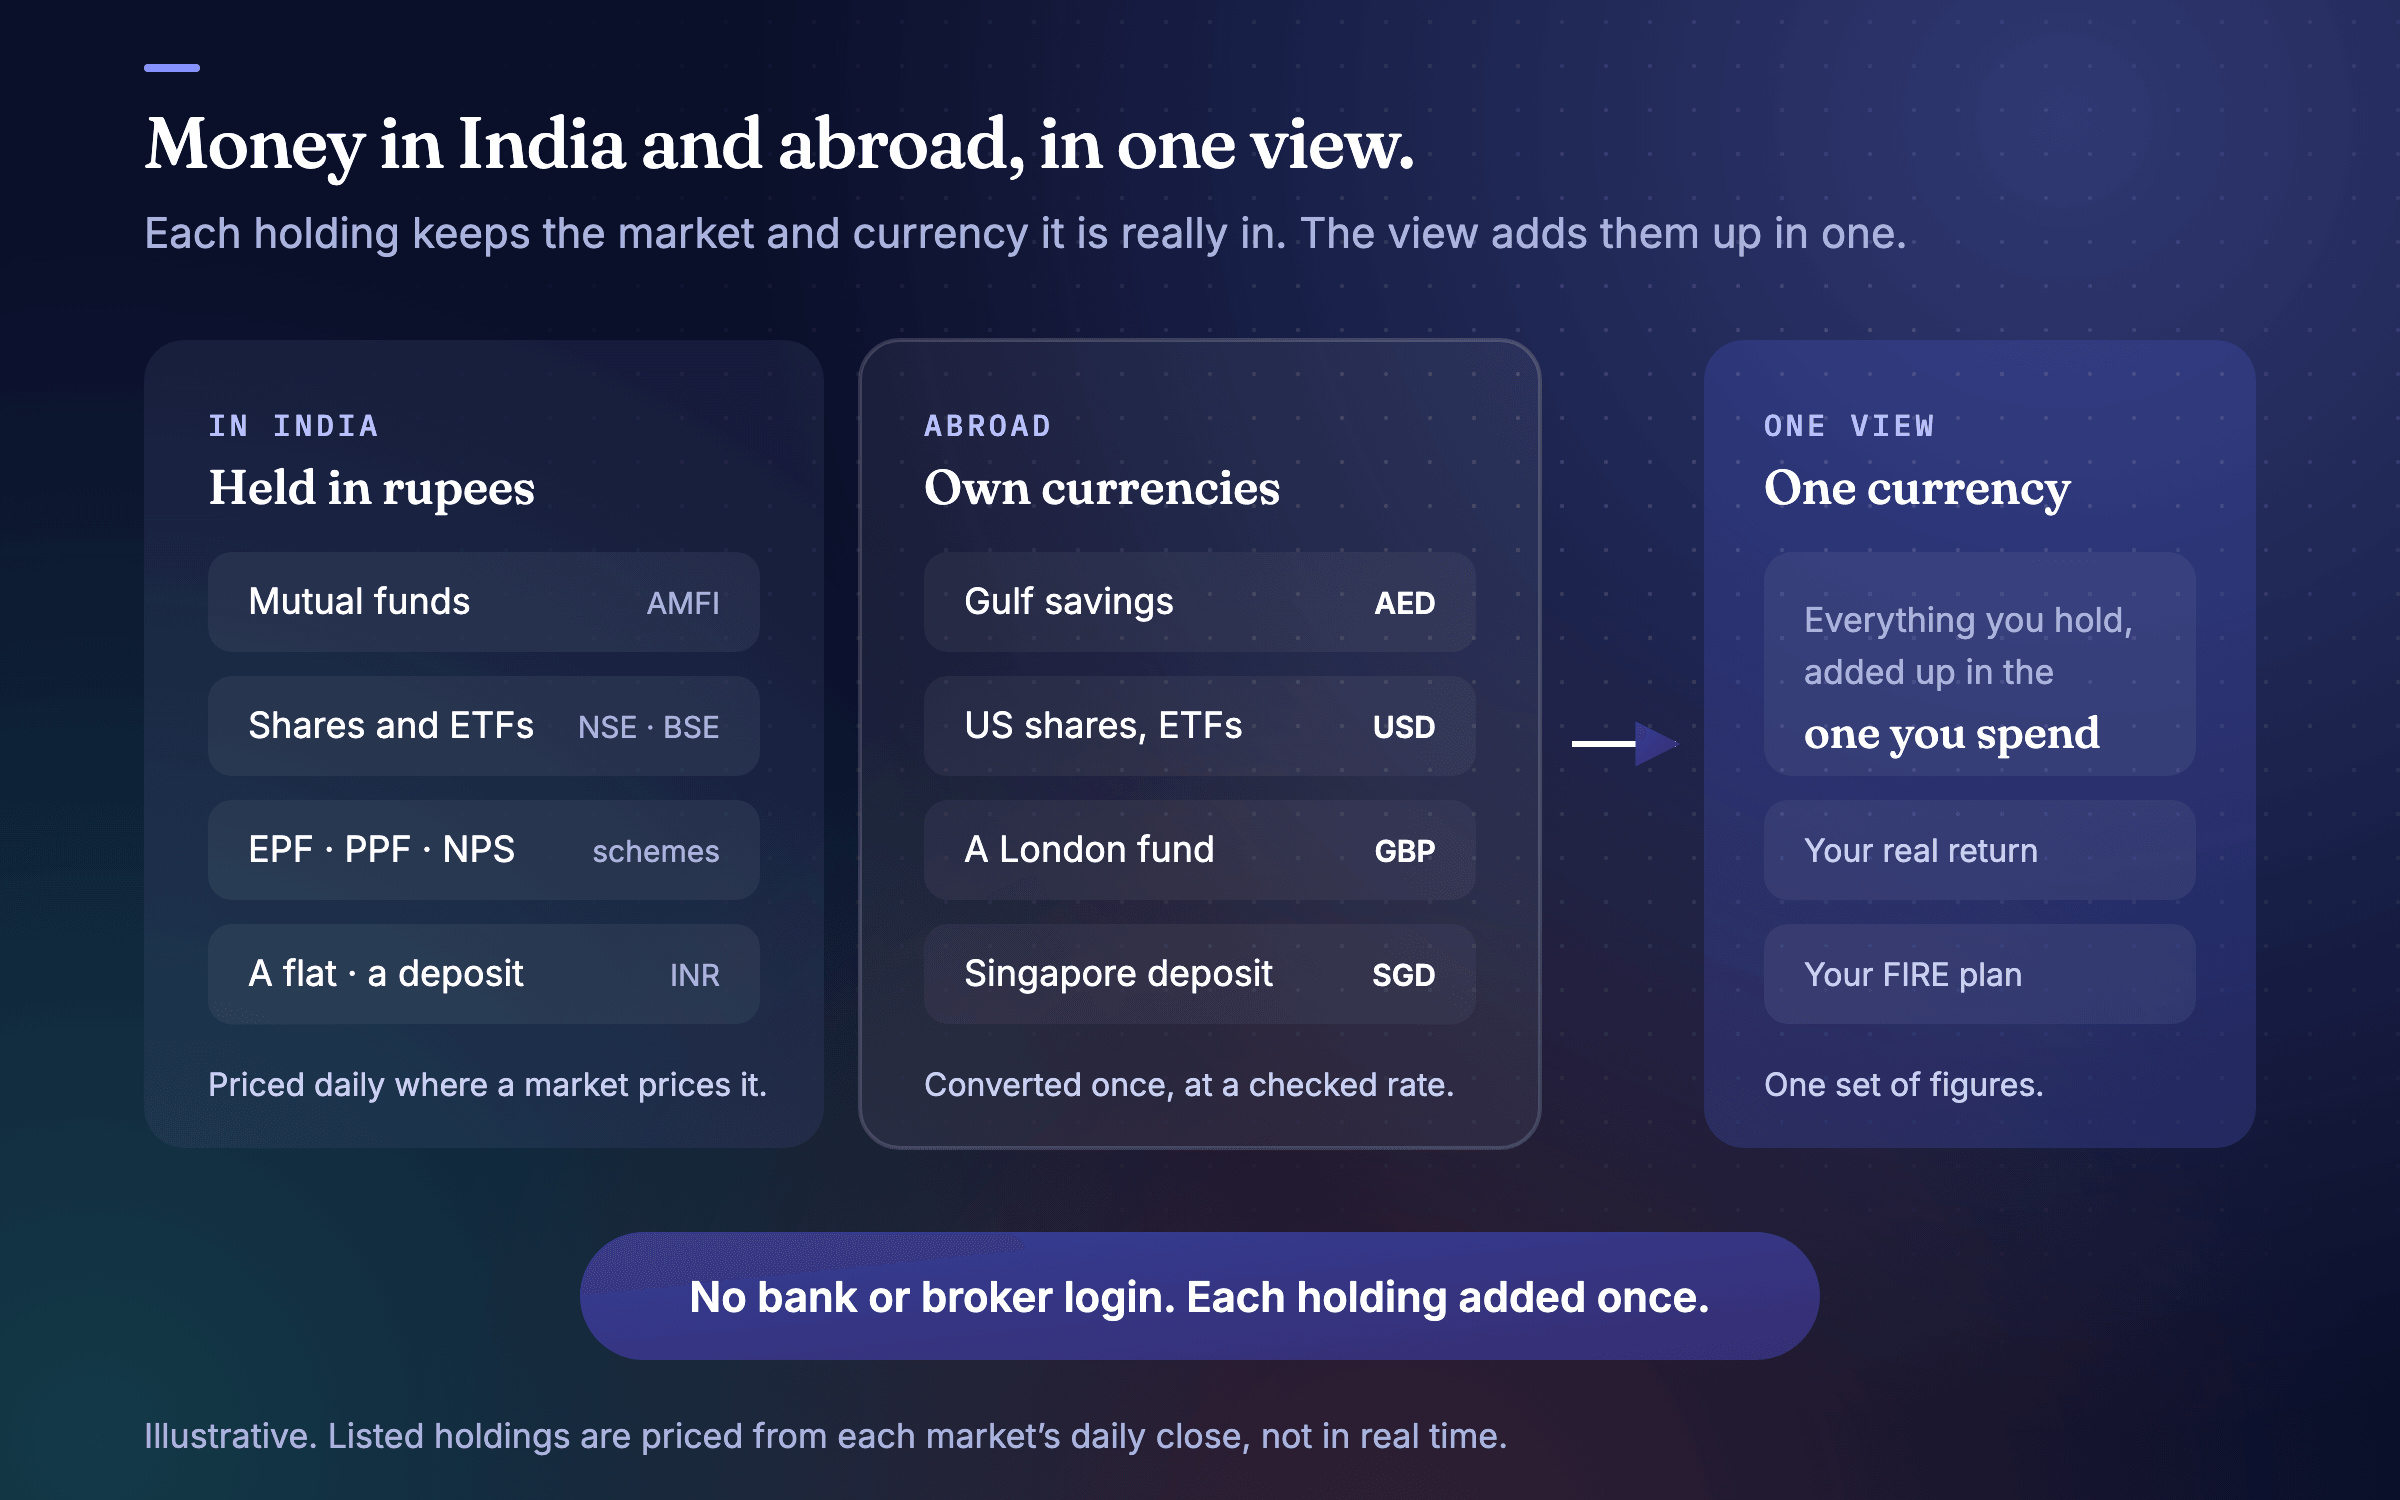
Portfolio Tracker · NRI net-worth tracker
Provident funds, pensions, gold, a rupee deposit and a dirham account: one net worth. A flat you live in counts for net worth; one you let out counts toward your corpus.
A marked emergency fund sits on the Freedom Ladder’s first rung, counted once.
Investments
FIRE Planner · financial planning for NRIs
Say where you earn today, where you will live when you stop working, and when you move. Salary, rent, school fees and loans each keep their own country, dates and currency.
Life after the move is priced at India’s rates.
Planning across countries →Your Location
When will you move to India?When I stop workingat 55
| Row | Where | Starts | Ends | As entered | In INR |
|---|---|---|---|---|---|
| Salary | UAE | Today | At 55 | AED▾ 30,000 / mo | ≈ ₹6.81L / mo |
| Rent from the Pune flat | India | Today | At the move | INR▾ 25,000 / mo | ₹25,000 / mo |
| Rent in Dubai | UAE | Today | At the move | AED▾ 10,000 / mo | ≈ ₹2.27L / mo |
| School fees | UAE | Today | At 52 | AED▾ 5,000 / mo | ≈ ₹1.14L / mo |
| Living in Dubai | UAE | Today | At the move | AED▾ 9,000 / mo | ≈ ₹2.04L / mo |
| Living in Pune | India | At the move | — | INR▾ 1,25,000 / mo | ₹1.25L / mo |
| Home loan | India | Today | Paid off 2037 | INR▾ 35,00,000 | ₹35L |
| S&P 500 ETF | NYSE | — | — | USD▾ 27,000 | ≈ ₹22.52L |
FIRE Planner · currency stress test
Your money abroad buys 15% less applies a 15% fall, on the day you stop working, to everything in another currency. For the illustrative household the plan lasts to 90, ₹4.27Cr lower.
Add a 2008-style crash and the two together take the plan to “runs out at 78”.
How the FIRE Planner works →FIRE Planner
Workable Lasts, with a modest cushion
| Age | Stage | Opening | Growth | Income | Outflow | Closing |
|---|---|---|---|---|---|---|
| 54 | Working | ₹6.14Cr | +₹59.92L | ₹1.2Cr | −₹98.7L | ₹6.96Cr |
| 55 | Retired | ₹6.96Cr | +₹53.69L | — | −₹29.75L | ₹7.19Cr |
| 56 | Retired | ₹7.19Cr | +₹55.53L | — | −₹30.94L | ₹7.44Cr |
Family Finance · plan it with your partner
Your partner joins with their own login, and each of you chooses whether the other can view or edit your side.
Invite your CA in India or a parent to see what you choose, read-only.
How Family Finance works →Family Finance
| Person | Age | Access |
|---|---|---|
| Your partnerPartner | 36 | JoinedPlanning together, with their own sign-in |
| Your motherParent | 64 | AcceptedSees: The family plan: every section and results |
| Your CAChartered Accountant | 51 | Pending approvalWaiting for your partner to approve · then it is emailed |
| A close friendTrusted friend | 40 | SentSent on 26 Sep 2026 · link valid until 10 Oct 2026 |
| Your brotherBrother or sister | 33 | Not invitedOn your plan · invite them to see it whenever you are ready |
Niv · free AI financial assistant
Niv reads your holdings, spending, buckets and plan. She runs each what-if on your own projection and reports both figures.
She explains, you decide. She never tells you what to buy or sell, and has nothing to sell you.
What Niv can do →Nivritee — call me Niv
What if I stopped working at 52 instead?
Then it does not hold — your savings would run out at 81 rather than lasting to 90. Your first year without a salary would be 2040, when Higher education — Child 2 falls due, so you would draw 18.9% of your savings that year against 4.3% on your plan as it stands. That is the difference between Workable and Short.
Ran a what-if · independence age 52
What only Nivritee does
Most trackers stop at one country, and FIRE calculators do not know what you hold. Here both read the same figures, in one currency. See the full comparison →
Indian mutual funds, US stocks, a UK fund and a Gulf deposit in one household figure, converted daily into your home currency.
What you hold today feeds the projection of when you could stop. Portfolio trackers do not plan; FIRE calculators do not track.
Two people, one plan, each choosing what the other sees — and your CA or lawyer sees exactly what you share, read-only.
Fourteen markets’ inflation, schemes and household surveys, so your spending and your percentile are measured where you live.
Ask Niv a what-if and she runs it on your own projection and reports both figures — she never guesses at arithmetic.
No fee, no commissions, no products. Nobody at Nivritee can open your plan.
Questions NRIs ask
Yes. Indian mutual funds are found by name or scheme code and valued at each day’s published NAV; NSE and BSE shares and ETFs are priced from the exchanges’ own daily files. You enter the units and what you paid once. There is no broker login and no statement upload.
Yes. Enter each account as a deposit, in the currency it is held in, naming the country it is banked in: a rupee account in India, a dirham account in Dubai, a pound account in London. Nivritee counts each balance and converts it at a checked daily rate; it does not treat one account type differently from another.
The currency of the country you will be living in when you stop working: rupees, for a household that will settle in India. Each holding and deposit keeps its own currency underneath and converts once, so the portfolio and the plan are always the same money.
No. Nivritee does not give tax advice and does not work out residential status, Indian or foreign tax, or treaty relief. It tracks what you hold and projects the figures you give it.
Choose when you stop working, an age of your own, or that you already live there, and change it whenever you like. Rows that stop at the move stop, rows that start there start, and nothing you typed is rewritten.
Yes. Free, with no paid tier, no commissions and nothing to sell. Nobody at Nivritee can open your plan or your holdings.
Free, neutral and private
Nothing here is for sale, so nothing here pushes you anywhere. You read the figures, and you decide.
Put India and abroad in one view.
Free, with no bank or broker login. About two minutes to a first plan from eight answers, then add each holding and account in the currency it is really in.