Nivritee Research

Personal finance, with the working shown.

Plain answers to the money questions families ask: how investing works, how much is enough to stop working, what the economy does to your loans, and what education costs. Every figure is sourced.

Retirement & FIRE

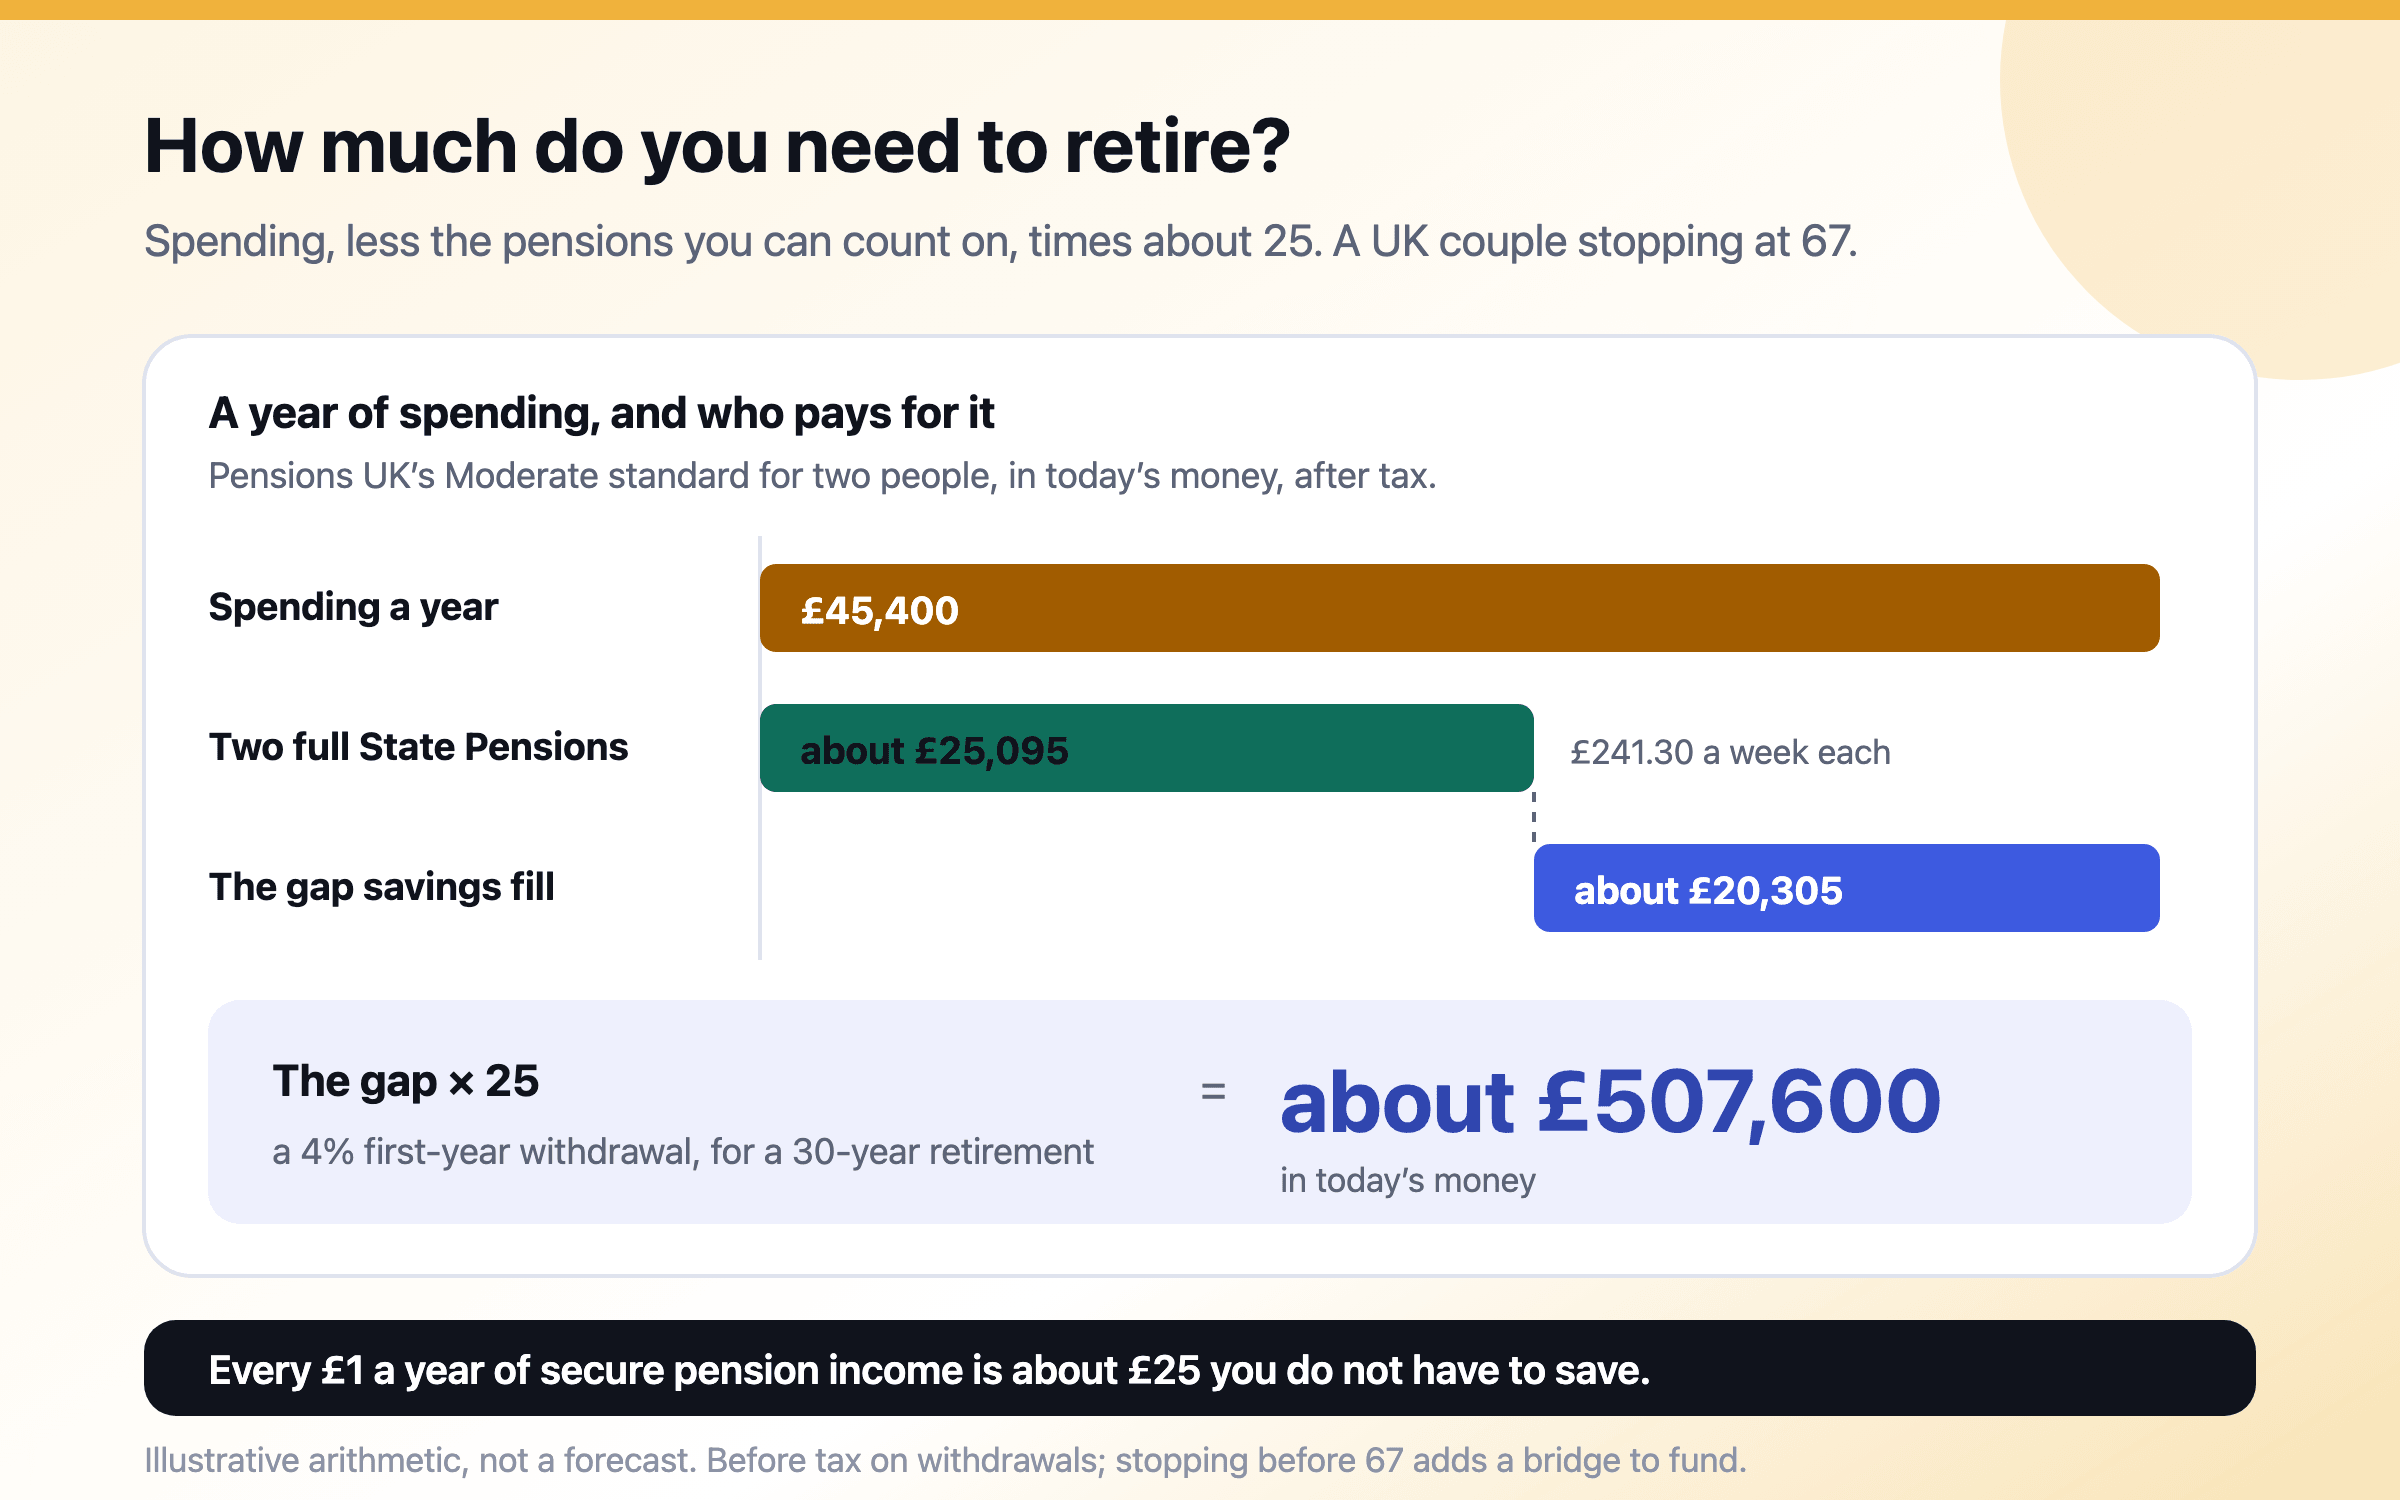
How much do you need to retire? A worked answer

Start from what you will spend, not from what you earn. Subtract the state and workplace pensions you can rely on, and multiply what is left by about 25 for a 30-year retirement, or by closer to 30 for a 40-year one. Real spending has tended to drift down about 1% a year through retirement while healthcare rises, and a 65-year-old today can expect to live another 15 to 25 years depending on country and sex — so plan for the long end.
Latest

New and updated research

The newest articles across every topic, each with its evidence and the households it was worked through for.

Money skills

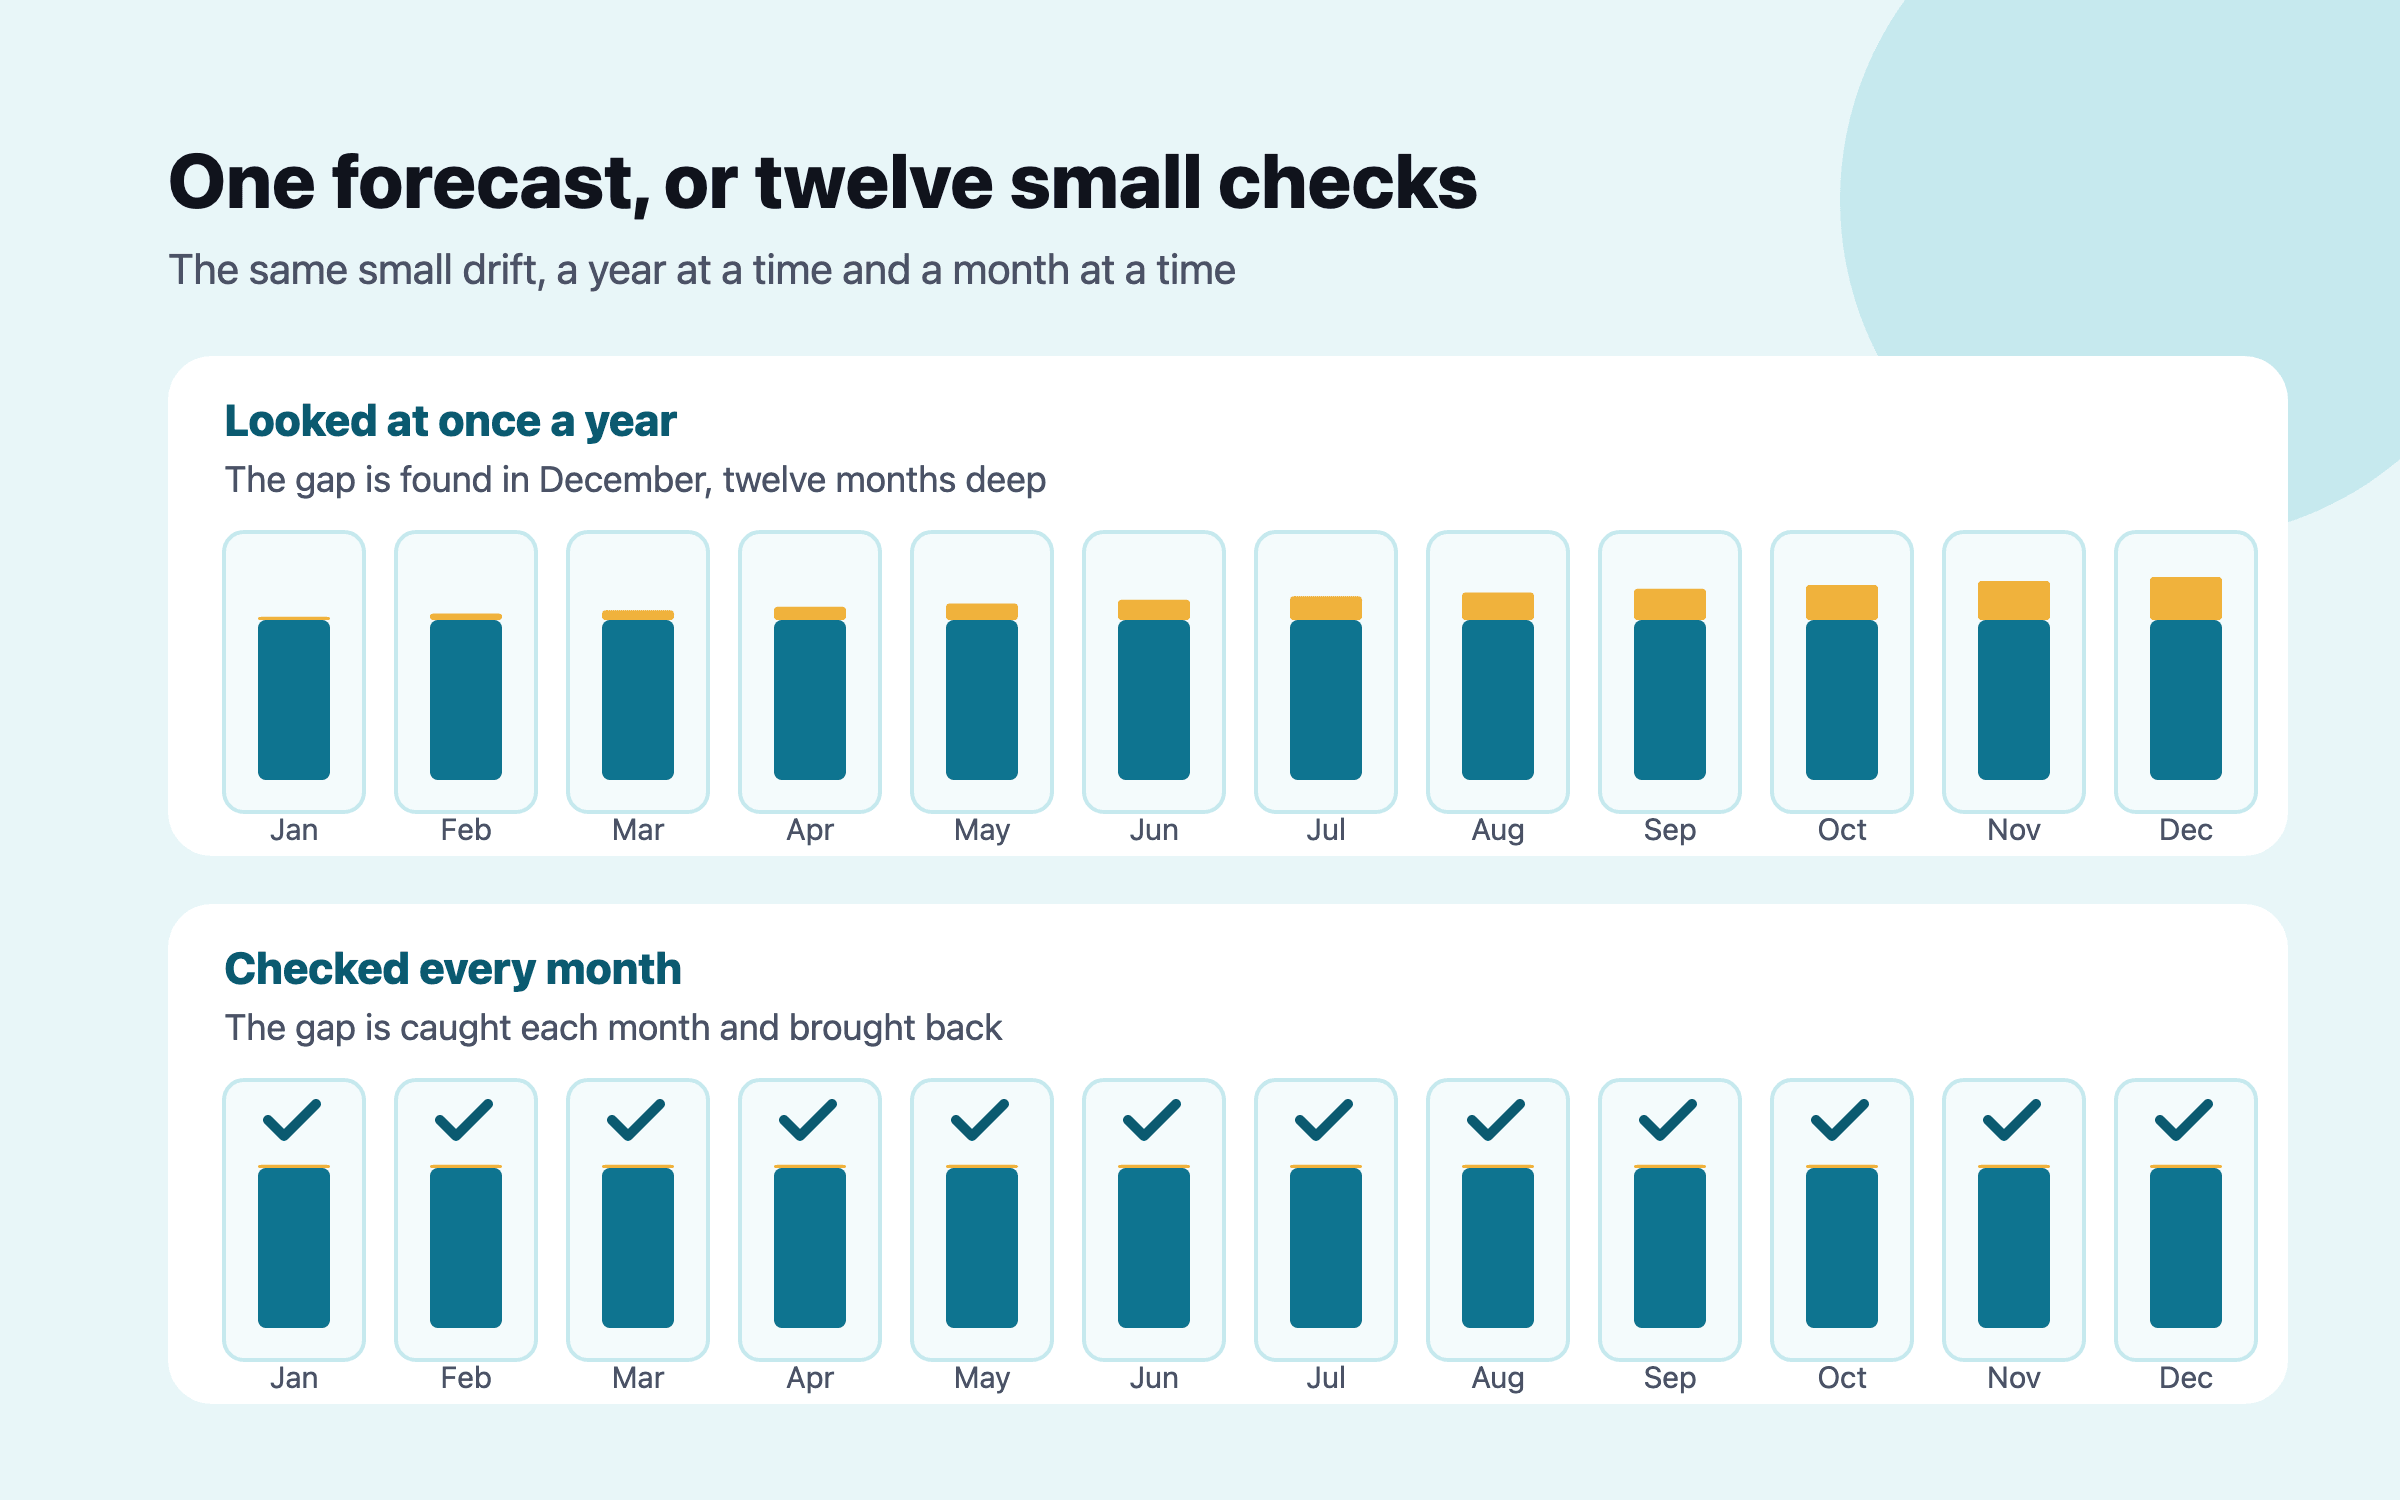
Why a monthly money check beats a yearly budget

People underestimate what lies ahead even when asked for a worst case: students in a classic study took 55.5 days over theses they expected to finish in 33.9. A yearly budget is that kind of forecast. A short check at the end of each month catches drifts while they are small, sees the irregular month coming and keeps every month on the record.

Family & behaviour

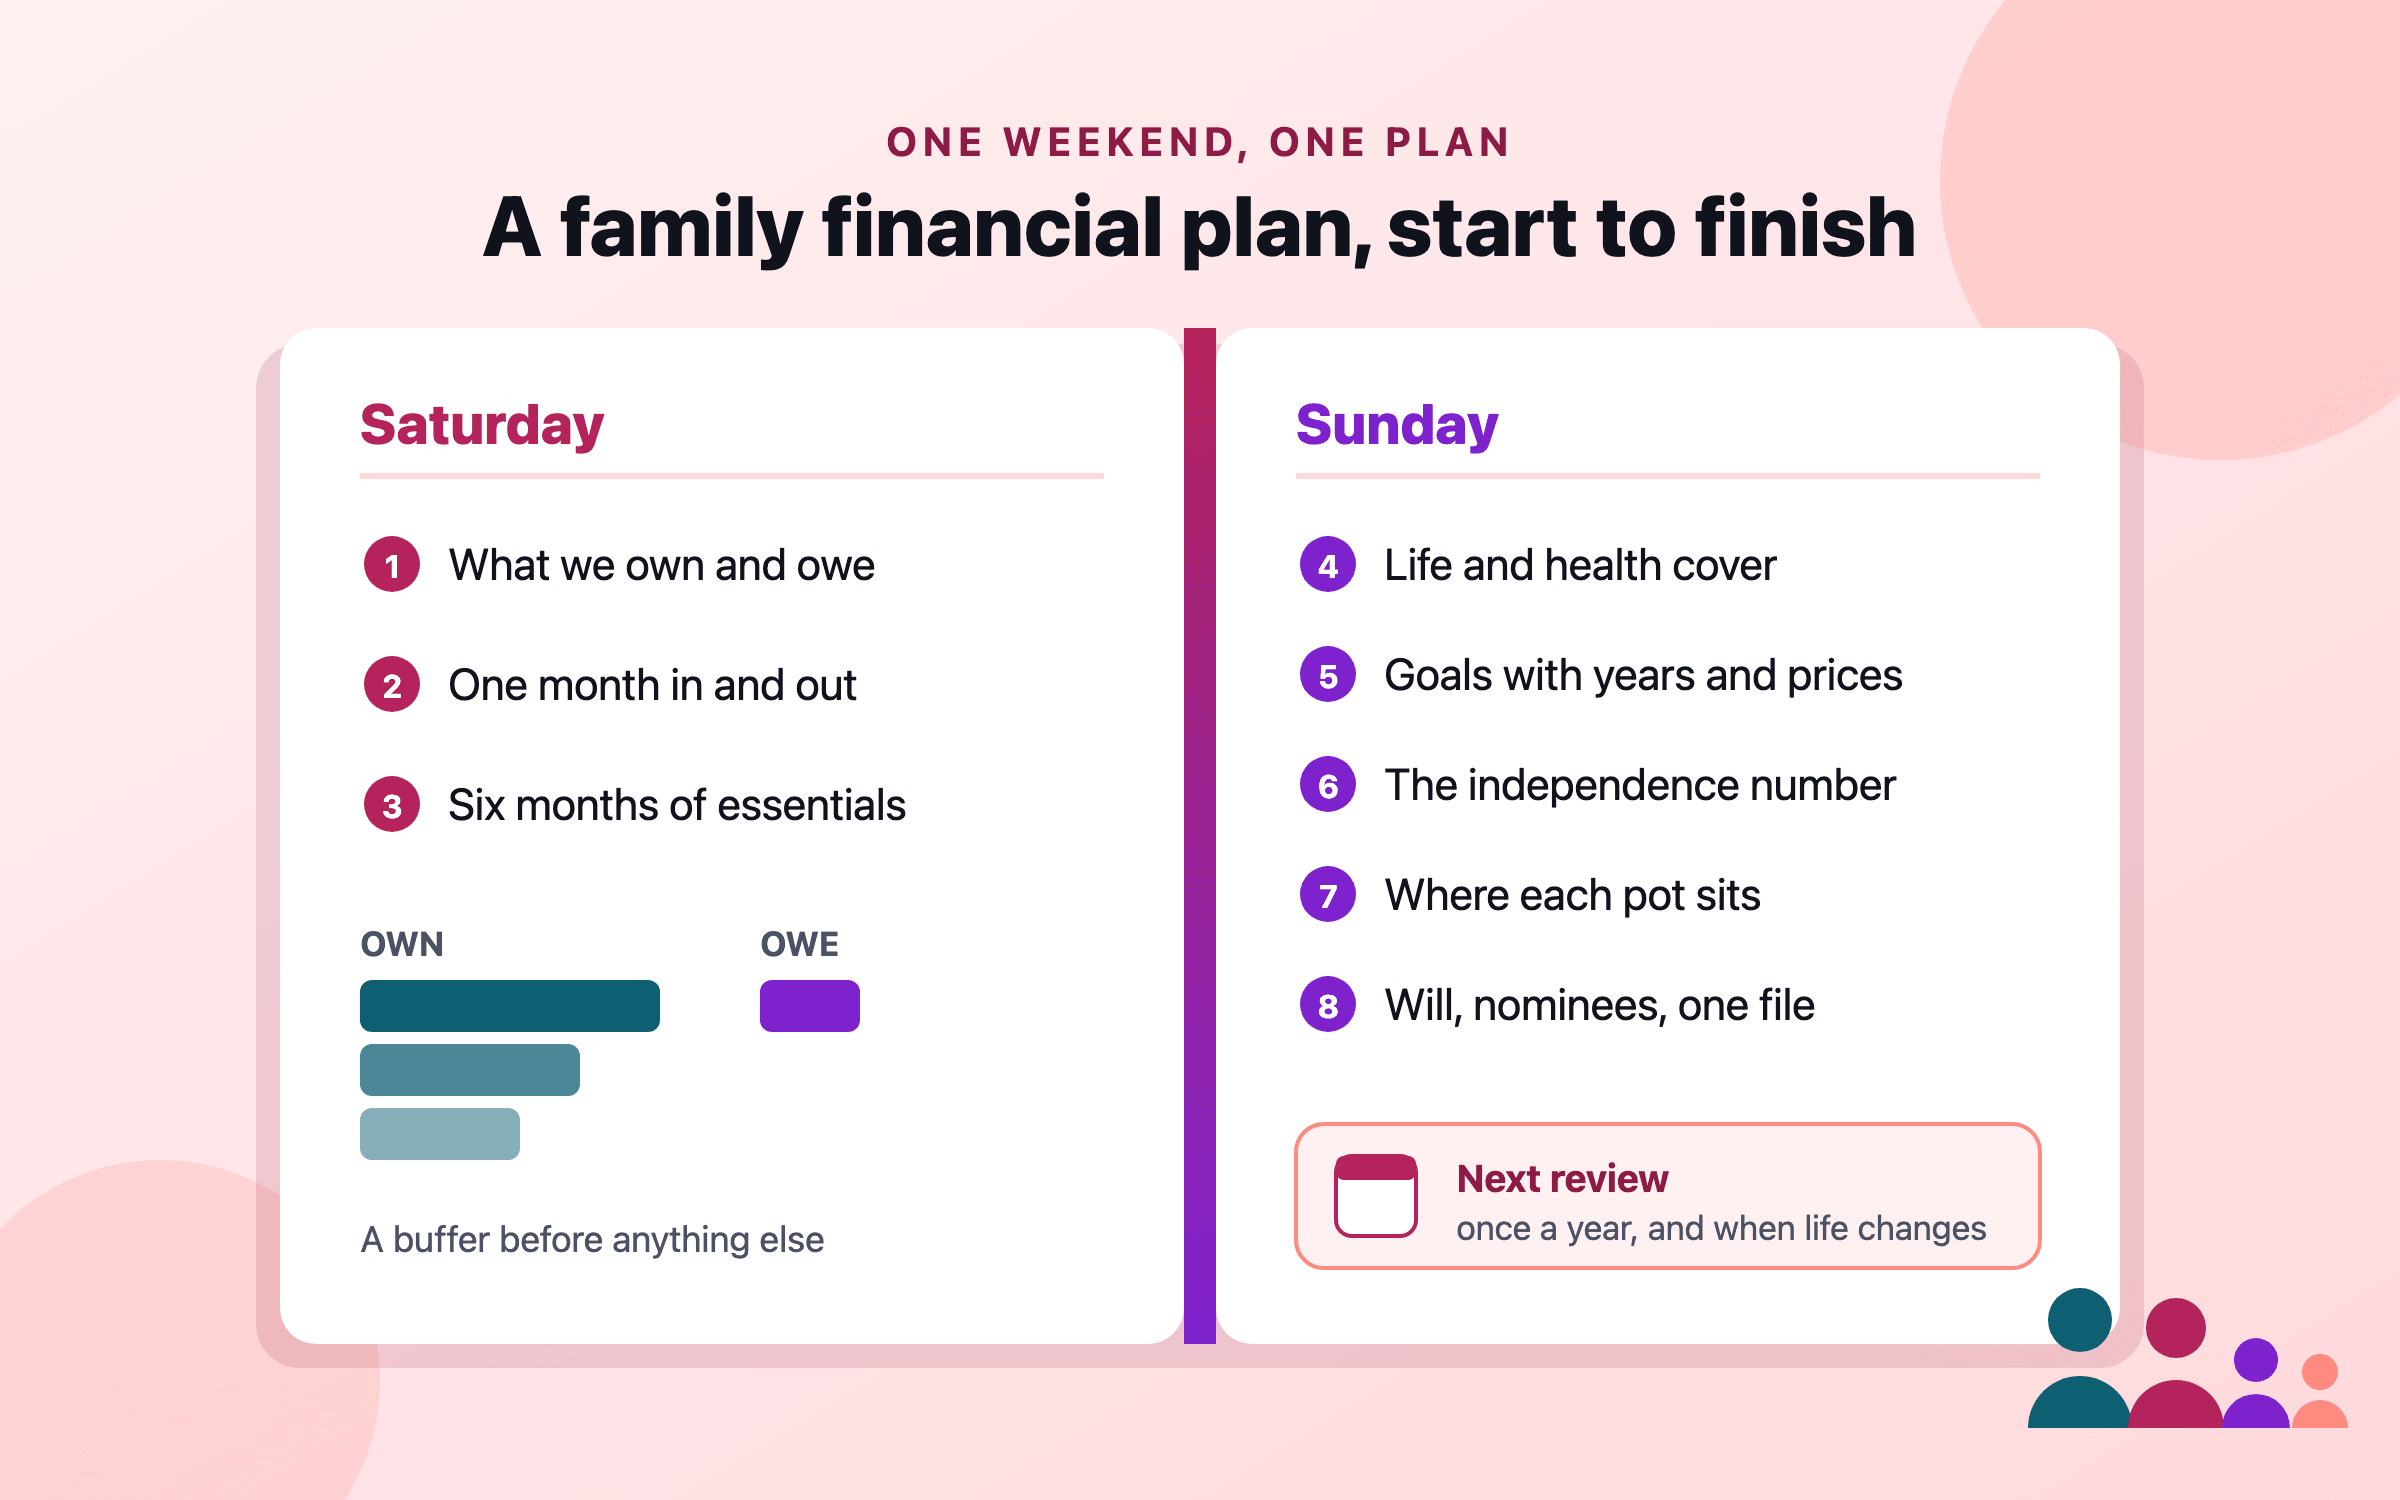
A family financial plan, start to finish

Sana and Arif, two earners with two children in Hyderabad, list what they own and owe, find a monthly surplus of ₹50,000, fill a six-month buffer, size term and health cover, price two degrees and a home in the years they fall due, and work out an independence number. The honest result is that the surplus covers the near goals and about a third of the far one, which tells them exactly which lever to pull.

Money skills

Managing money month to month without the stress

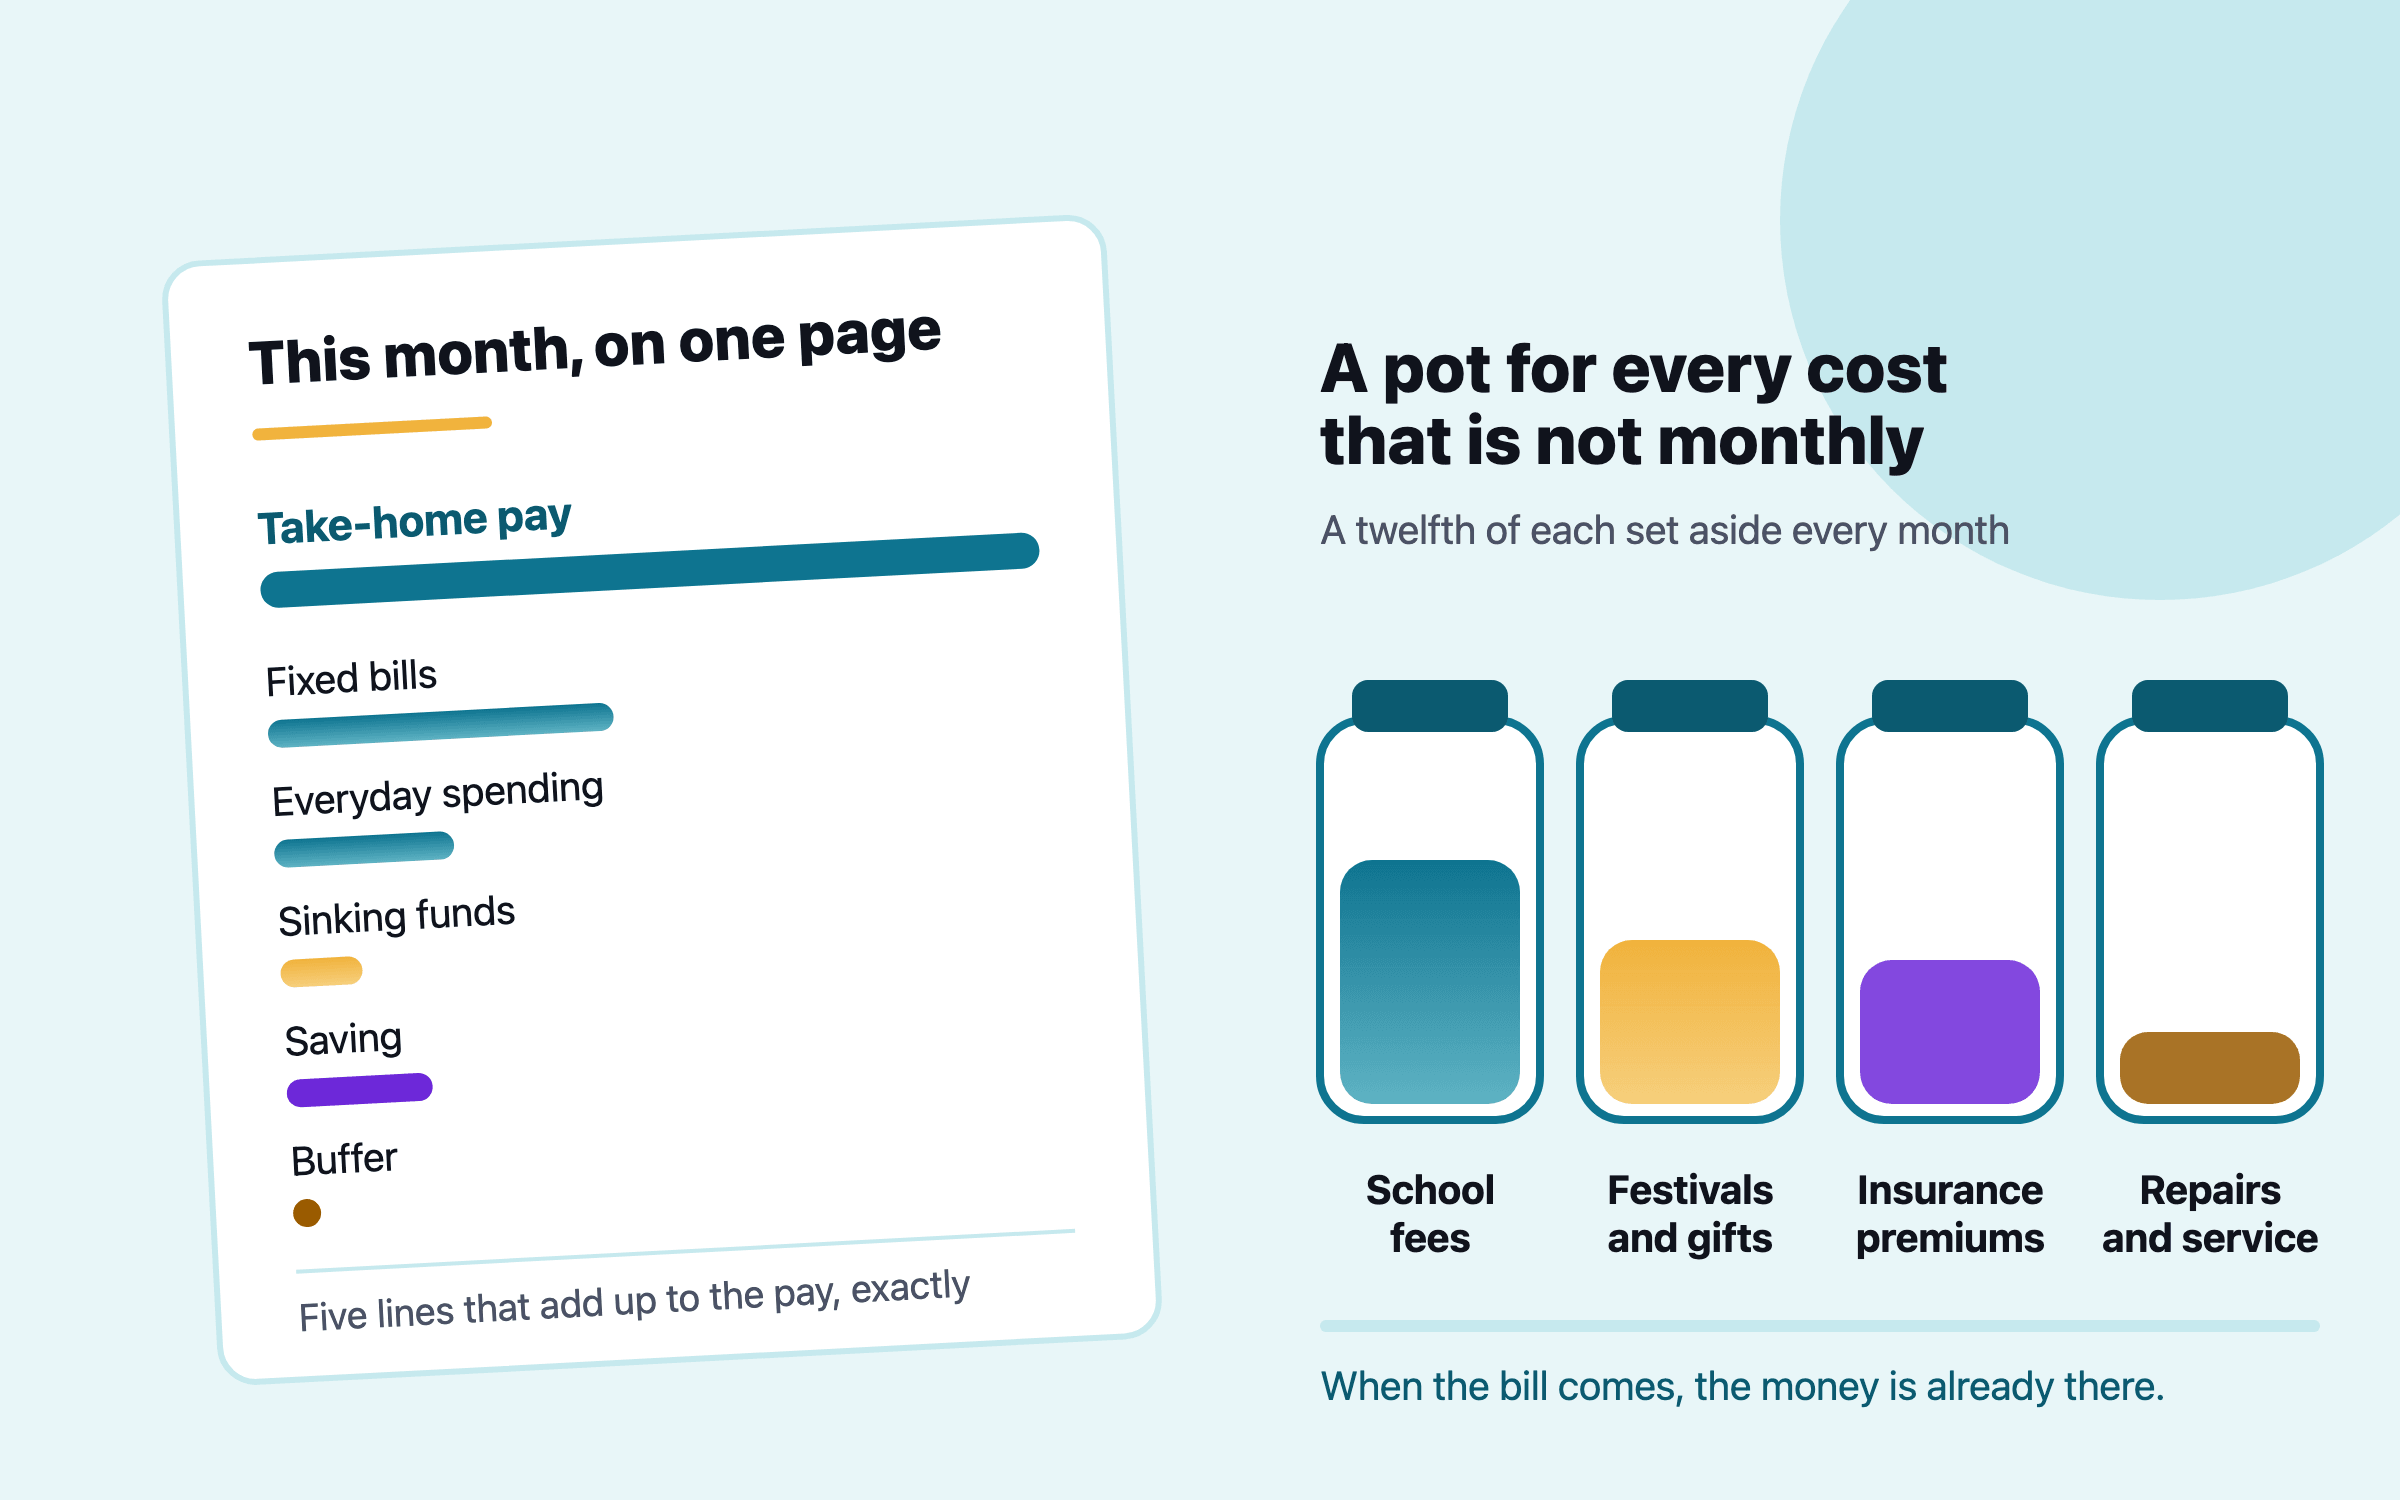
In the APA’s 2026 survey 77% of US adults called the cost of living a significant source of stress, and September prices rose 3.7% in the US and 5.54% in India. A Mumbai family shows the fix: one page for the month, a pot for every irregular cost, payday automation and twenty minutes a week.

Retirement & FIRE

Long-term plan, short-term storm

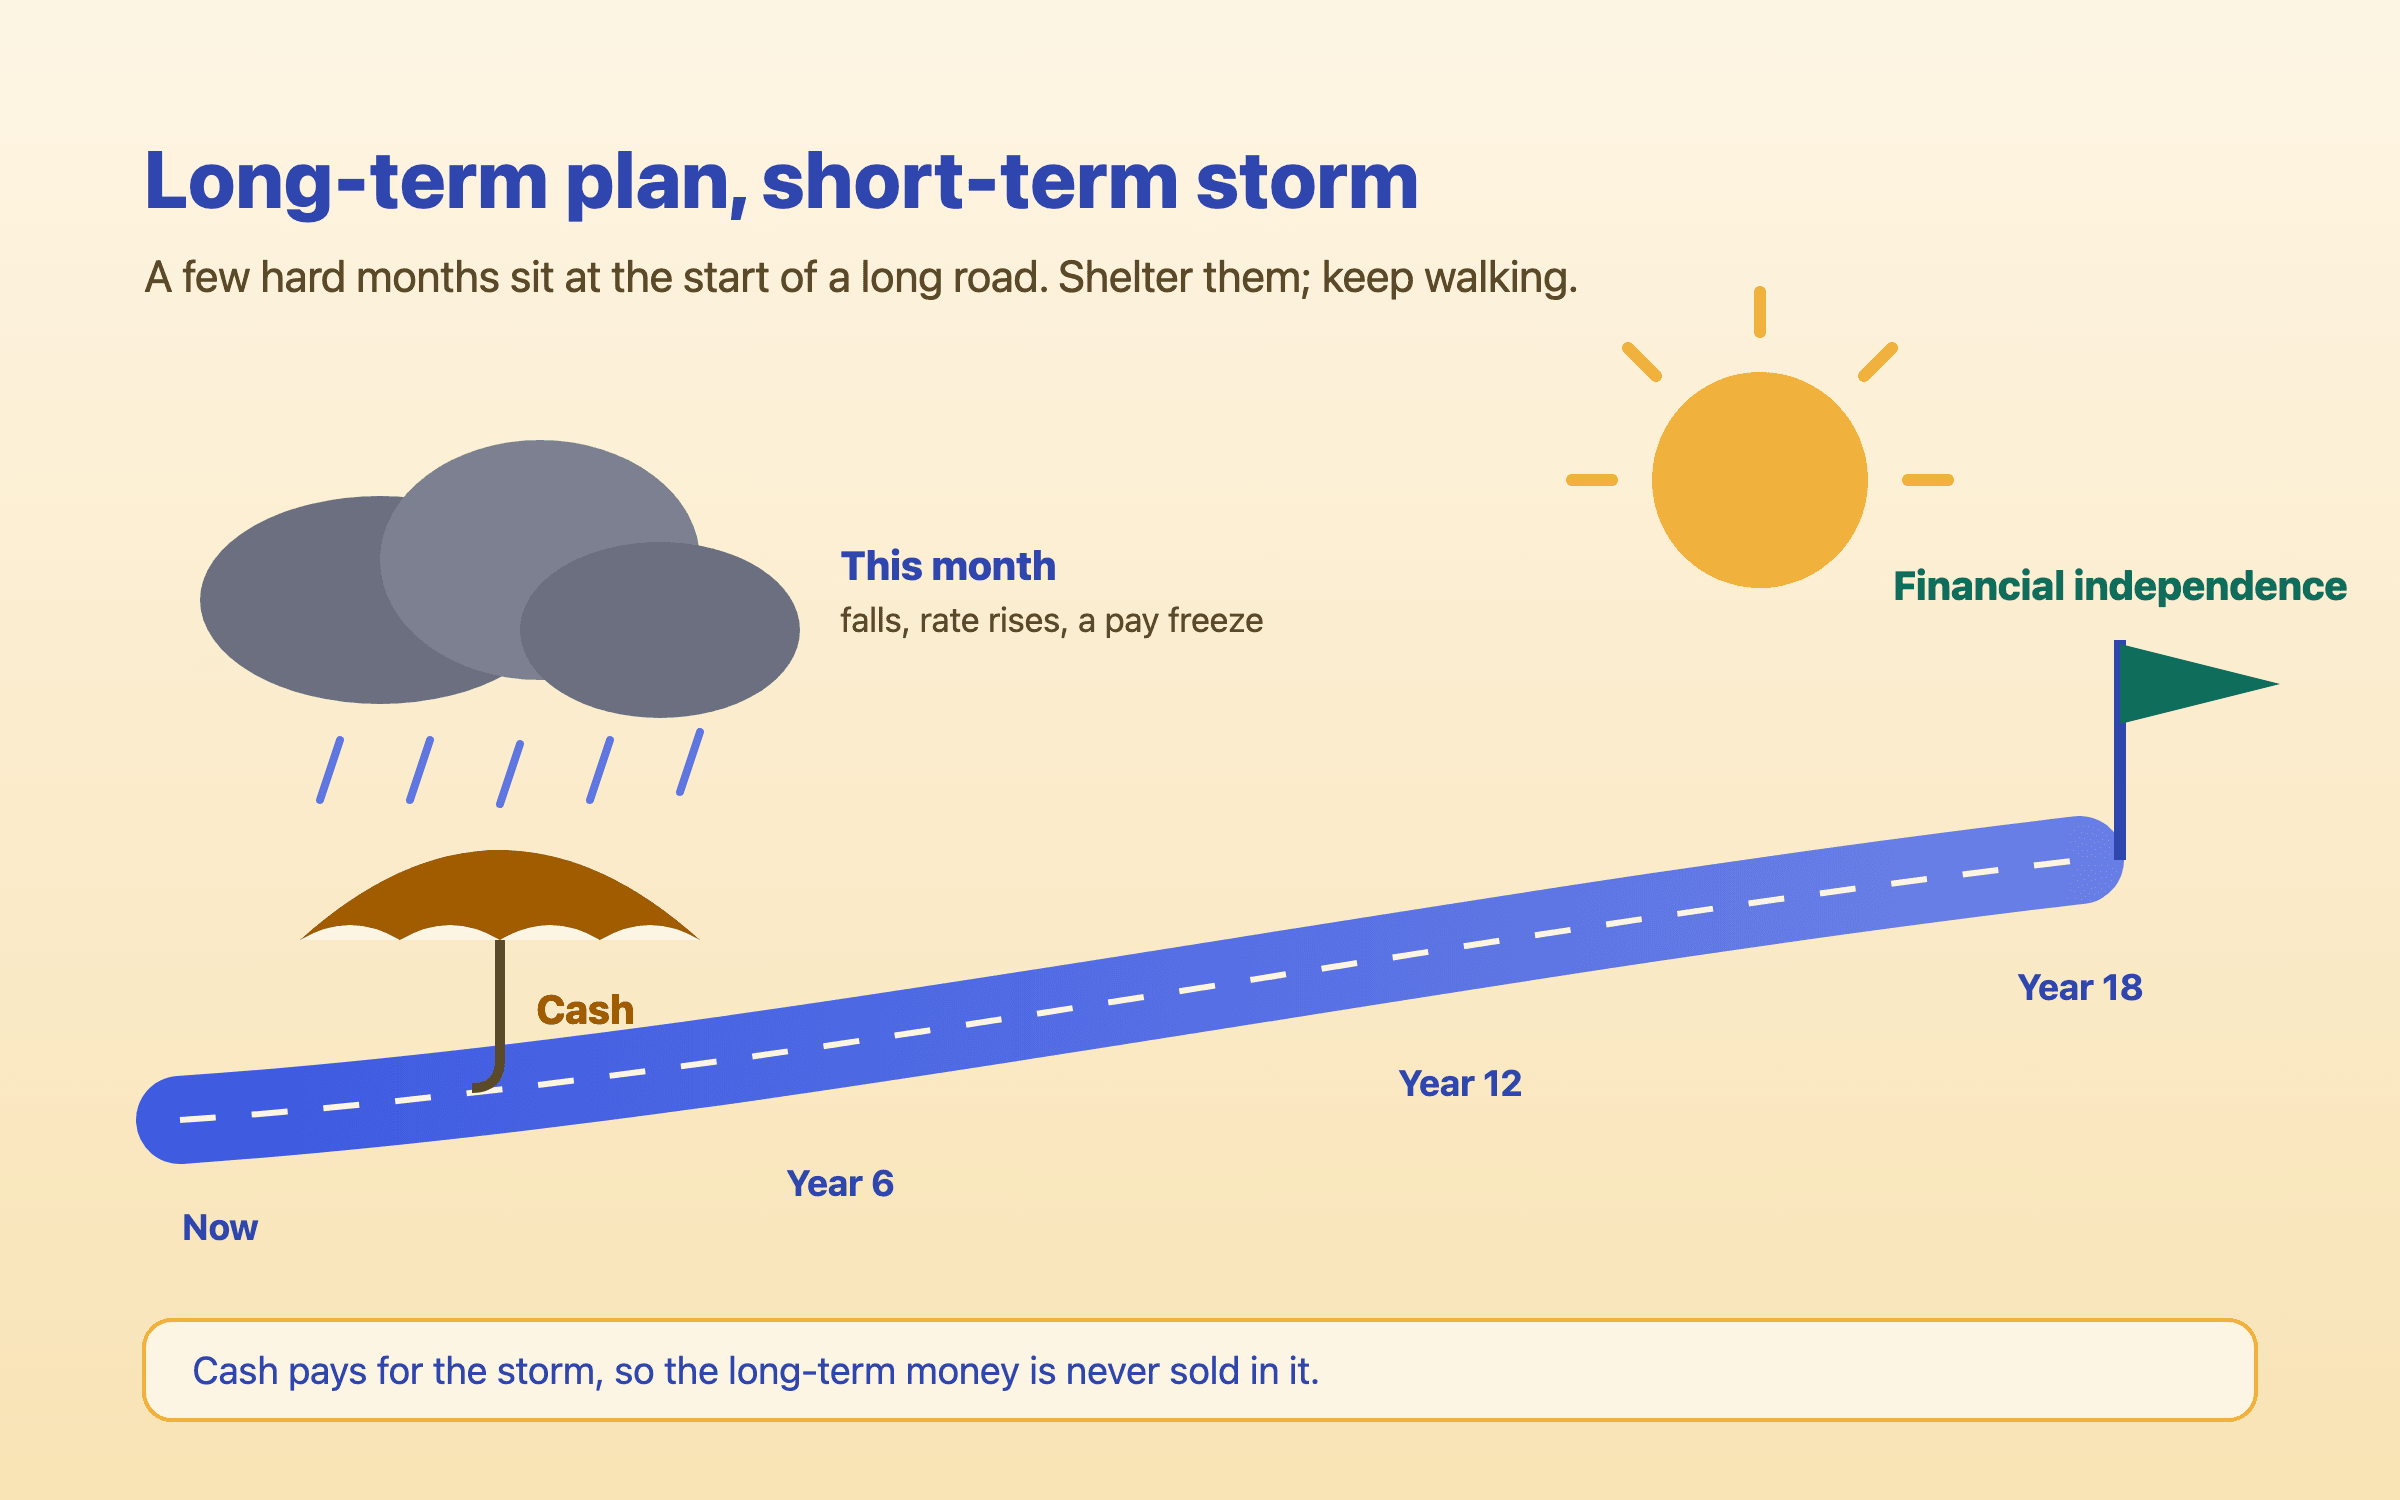
In a bad month the choice feels like all or nothing, and it is not. For an illustrative Delhi couple with 18 years to go, pausing a ₹40,000 SIP for six months leaves 97% of the plan and delays it about four months, while stopping for good leaves 52%. The pause is often the right call if it buys the cash that keeps long-term money from being sold in a fall.

Data reports

The baht over 25 years: a report for Thais abroad

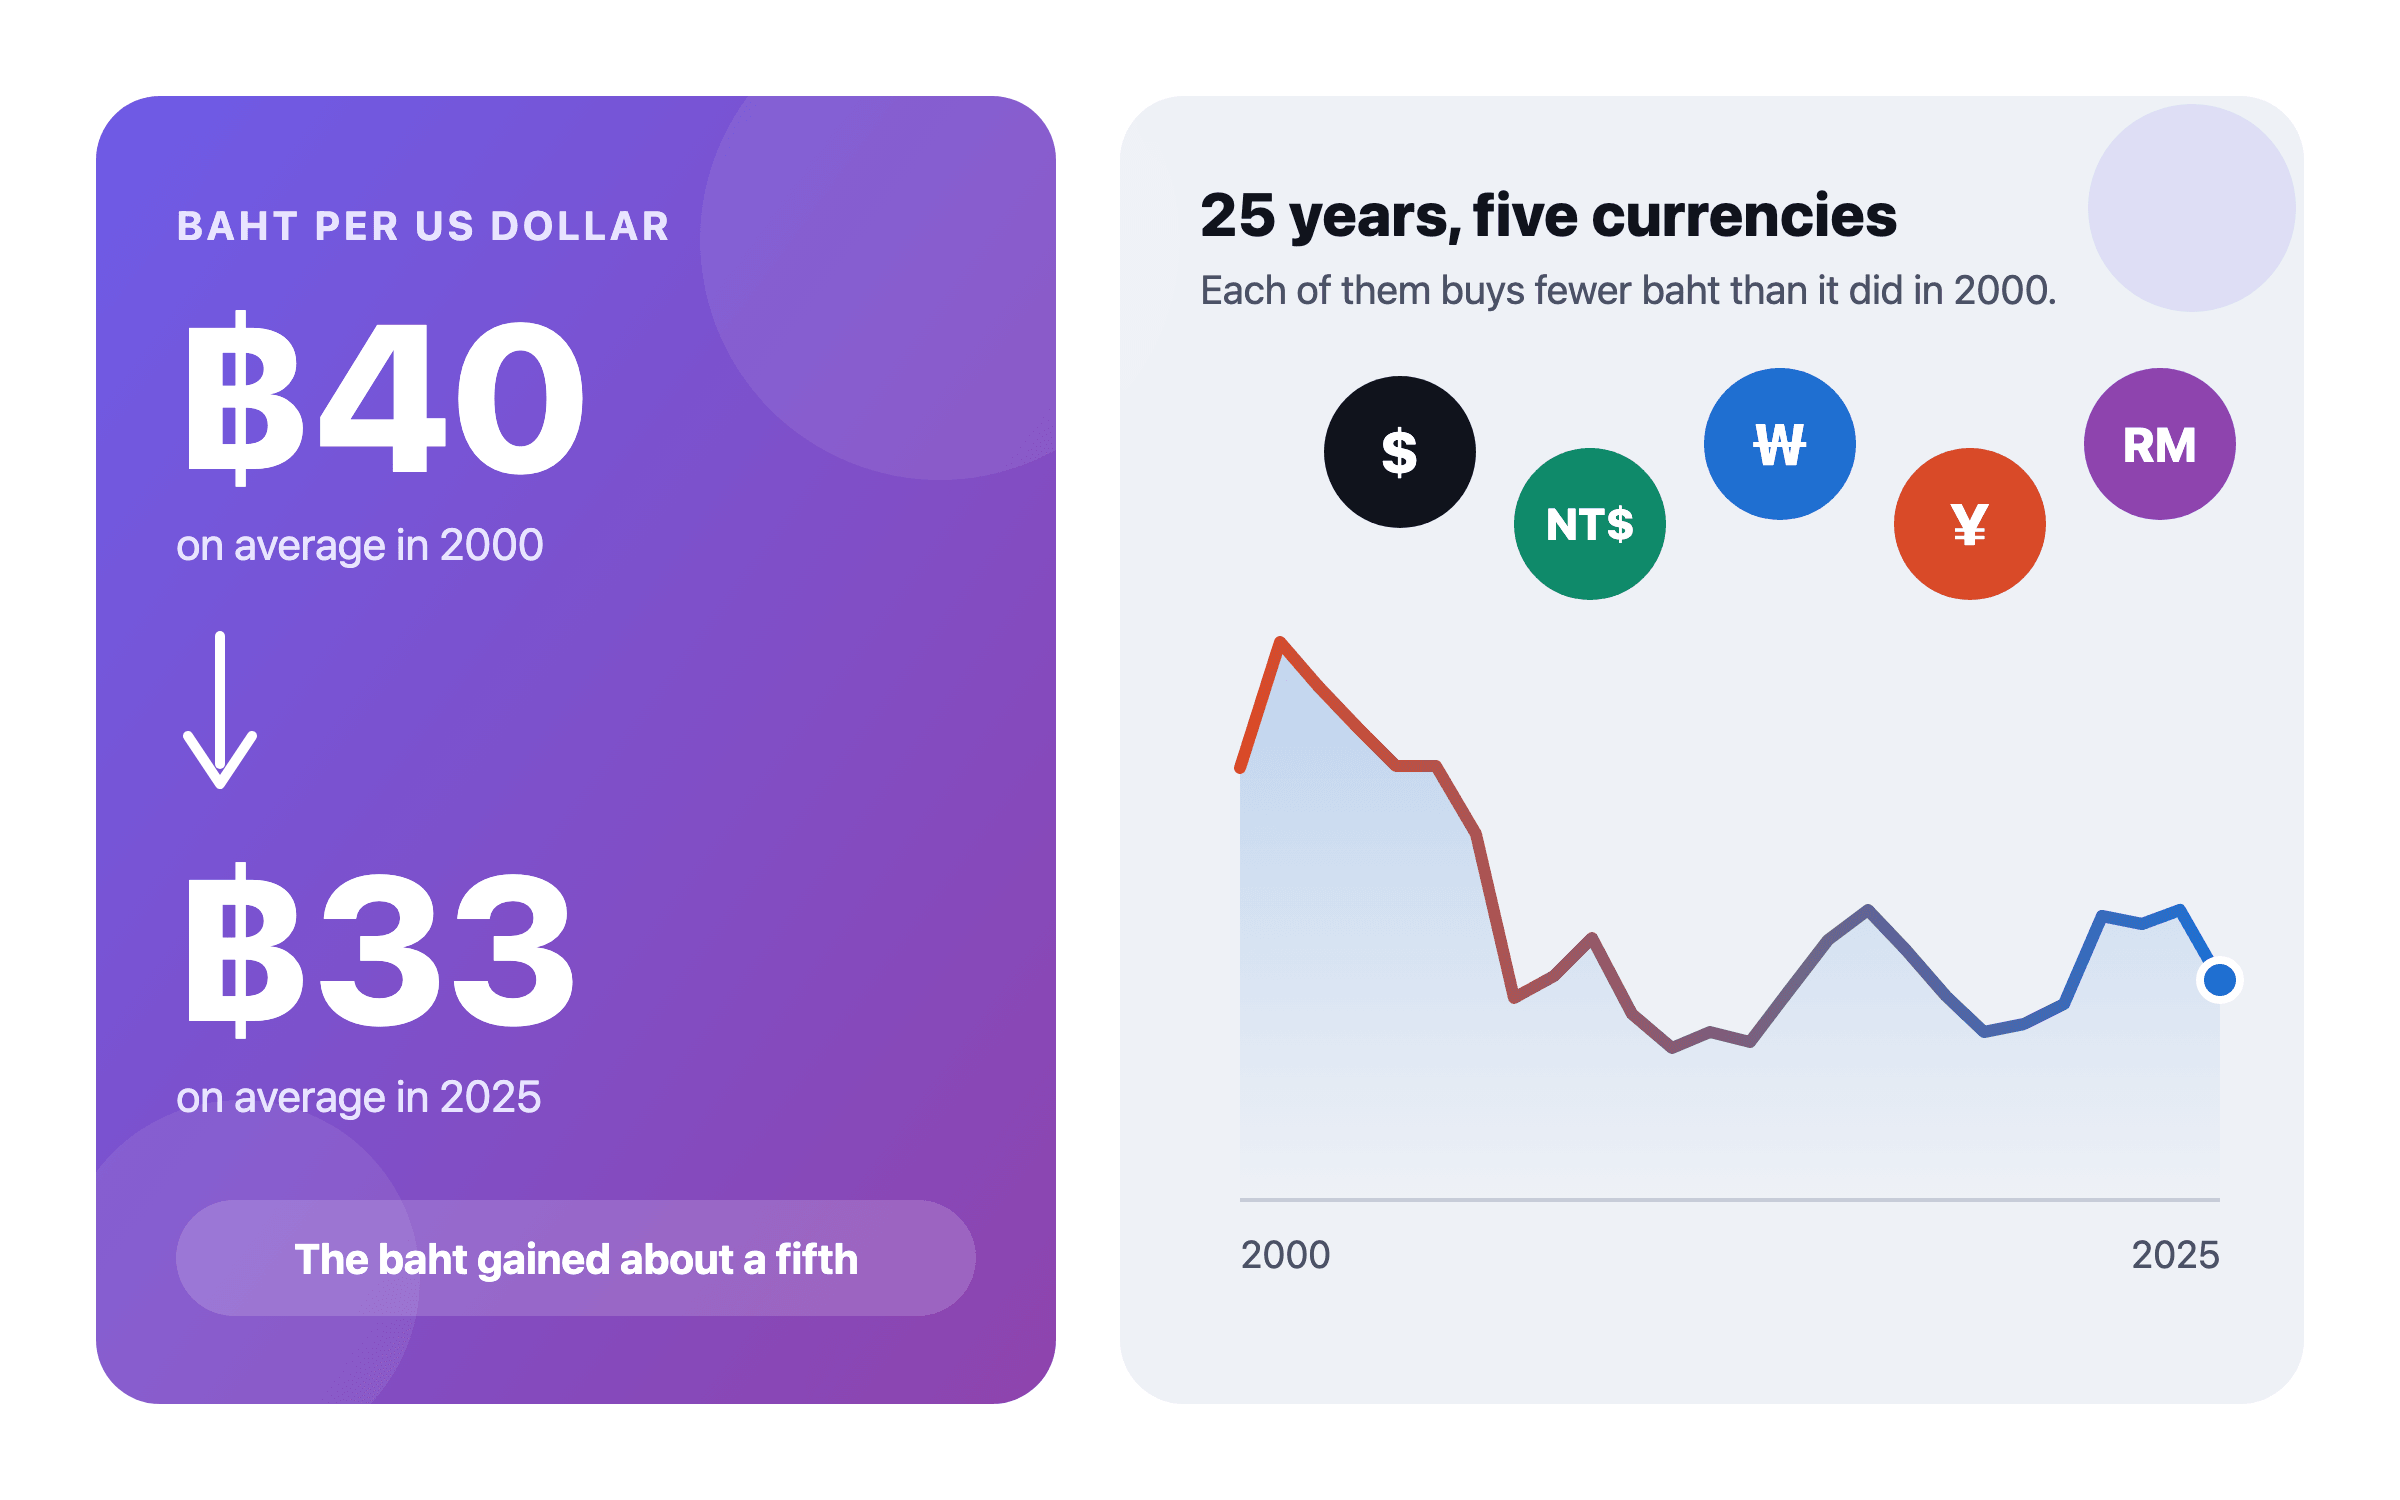
A dollar bought ฿40.21 on average in 2000 and ฿32.86 in 2025, and 100 yen fell from ฿37.30 to ฿21.97. Lower inflation in Thailand than in the US explains the direction. For a Thai earning abroad and spending in baht later, the lesson is to judge savings in baht, the currency they will finally be spent in.

Global & NRI money

Sending money home to Thailand: what it really costs

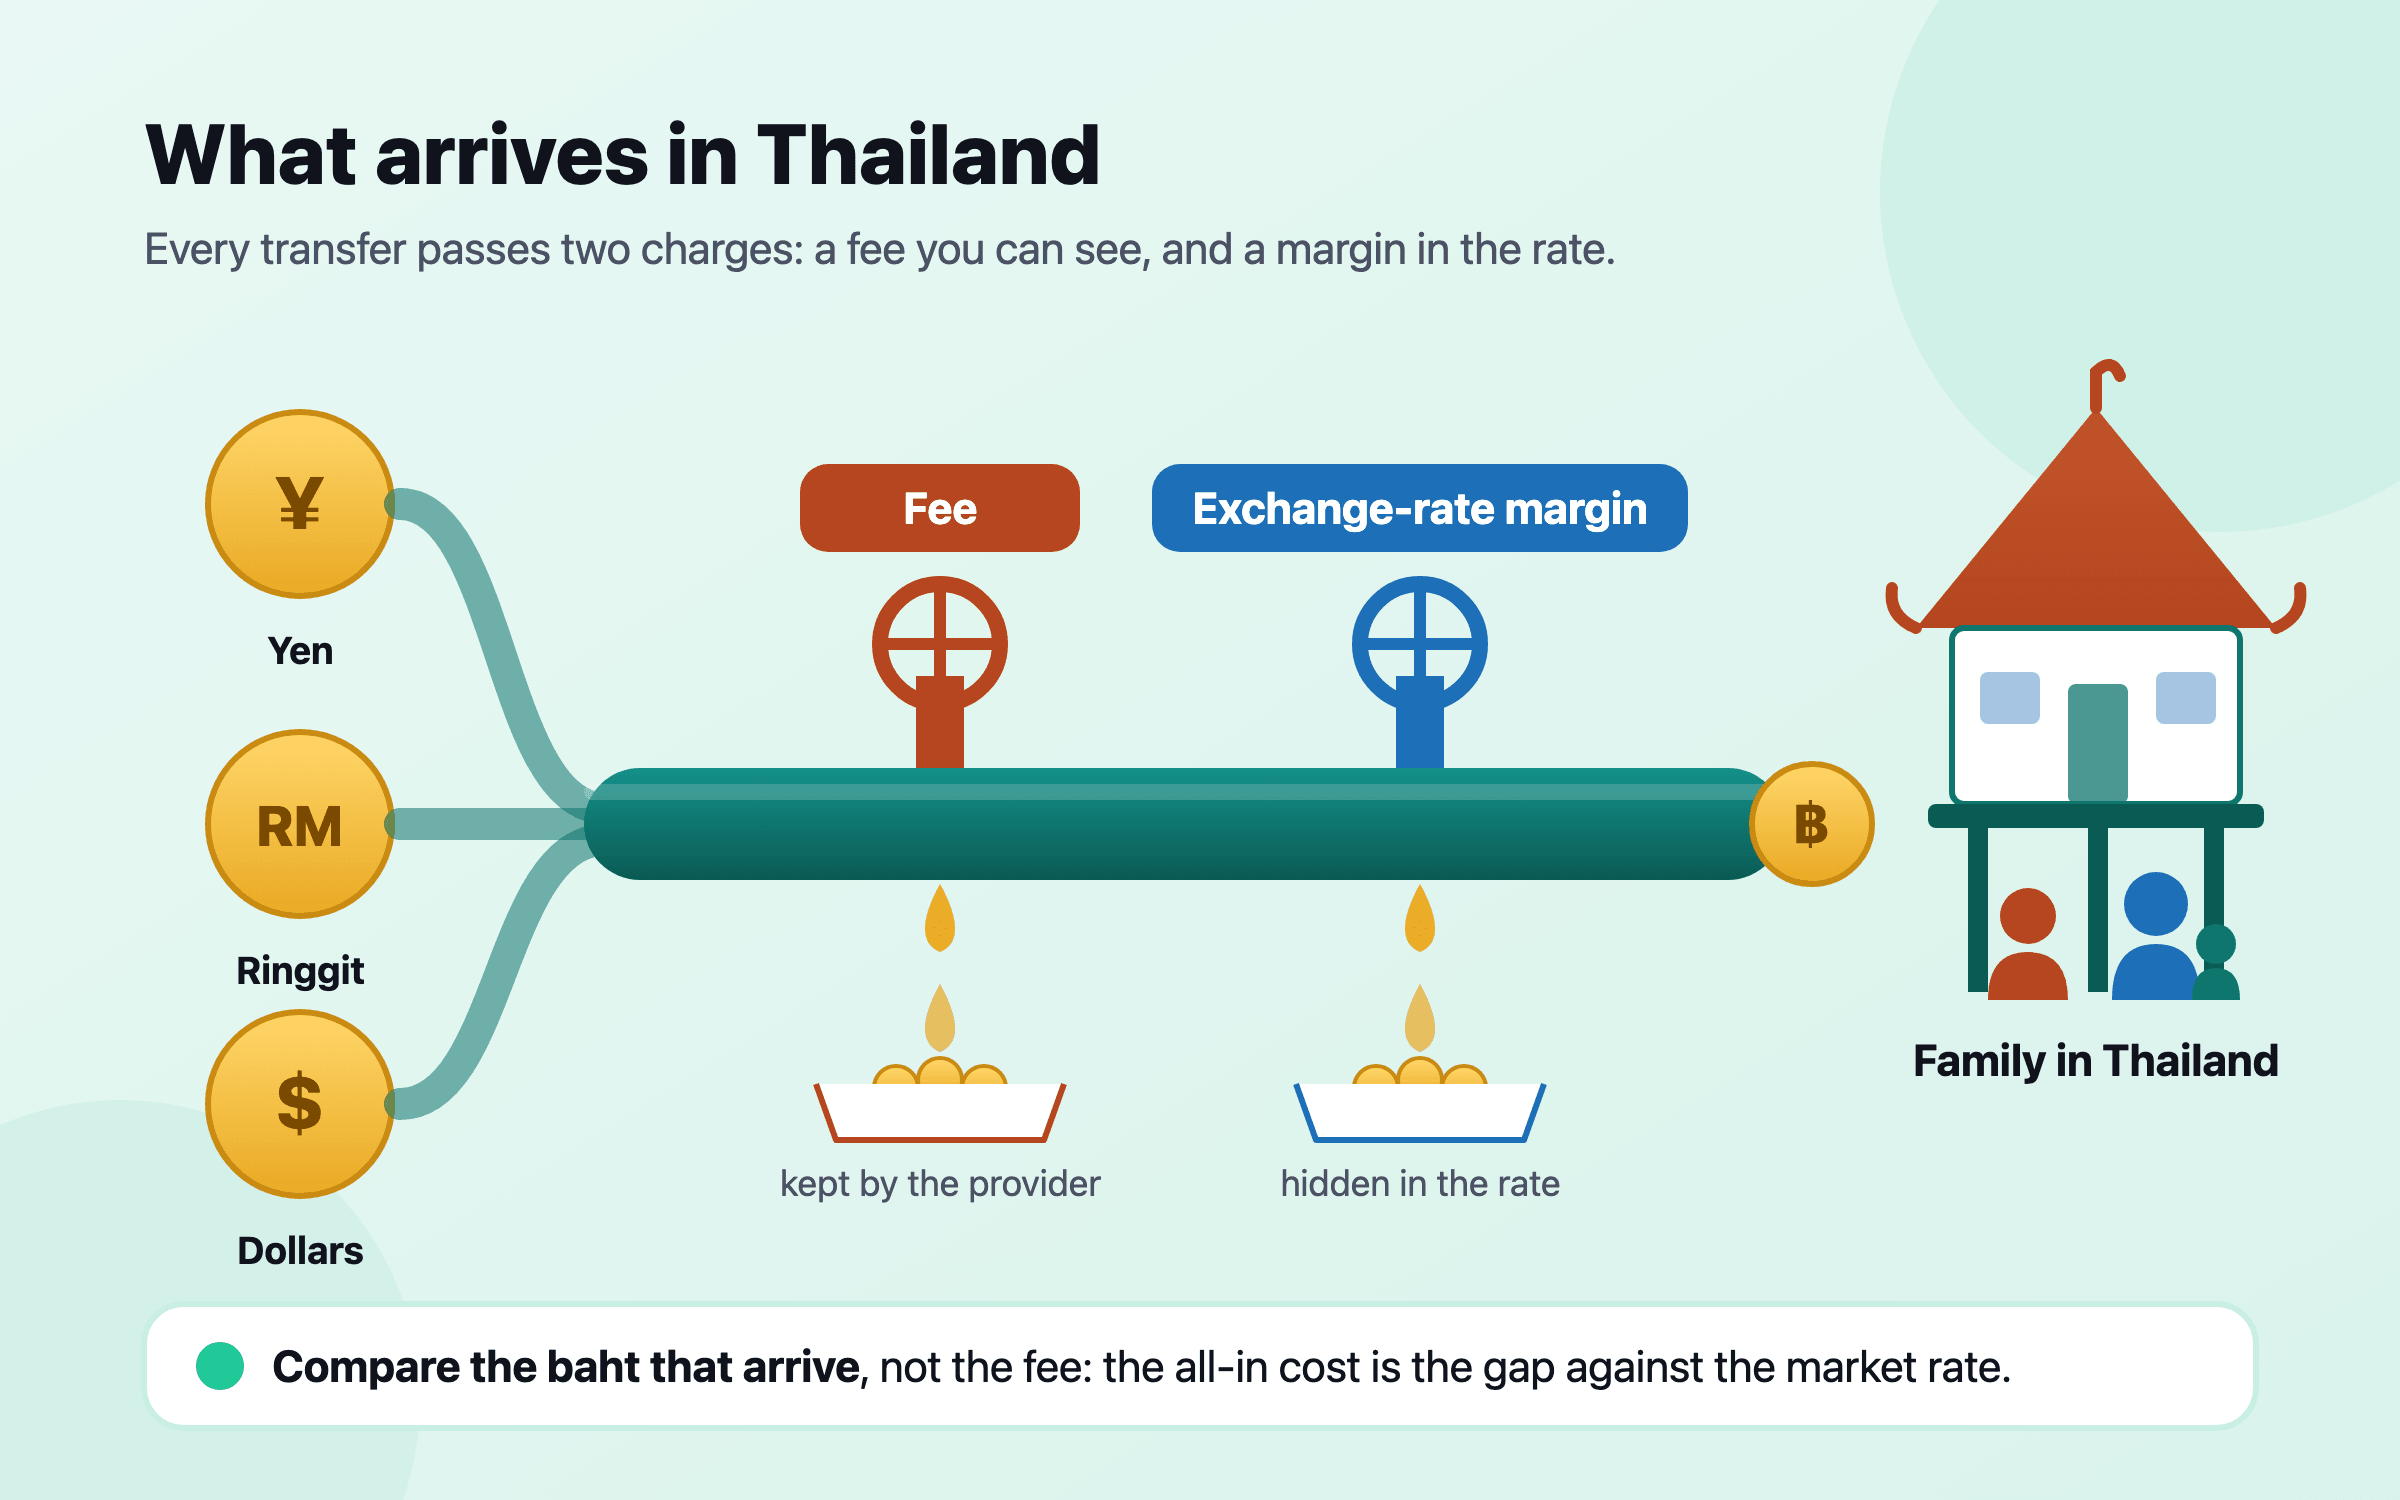
Sending the equivalent of $200 to Thailand cost 5.82% on average in the third quarter of 2025, down from 9.17% in 2017 and now below the world average of 6.36%. The seven corridors the World Bank prices run from 4.20% from Australia to 8.33% from Japan, while the three cheapest services in each cost between 1.31% and 4.68%. Compare the baht that arrive, not the fee.

Browse by topic

Nine topics, every article

Each topic has its own page with every article in it.

How we work

Before we publish a number

It has a source, or it does not appear

Every figure in an article cites its source, and a test fails the build if one does not. Authors are summarised and credited, never reproduced.

Missing is missing

Nothing is interpolated or borrowed from another market to fill a gap. A plausible invented figure is worse than an obvious hole, because only one of them is visible.

Information, not advice

Research explains how things work and what the evidence says. What to do with your money depends on you, your plan and a licensed professional.

Free, neutral and private

Family-office thinking, free for every family.

Nothing here is for sale, so nothing here pushes you anywhere. You read the figures, and you decide.

  • We don’t sell financial products.No commissions, no funds of our own, no referral fees.
  • We don’t sell data. We don’t run ads.No amount from your plan goes into an email or an analytics tool.
  • Nobody at Nivritee can open your plan.There is no screen that could show it to us.

Now run the numbers on your own money.

Nivritee projects your family’s plan in the country you will live in, tracks every investment in one currency, and shows where each pound, dollar or rupee should sit. Free, and nobody here reads your plan.